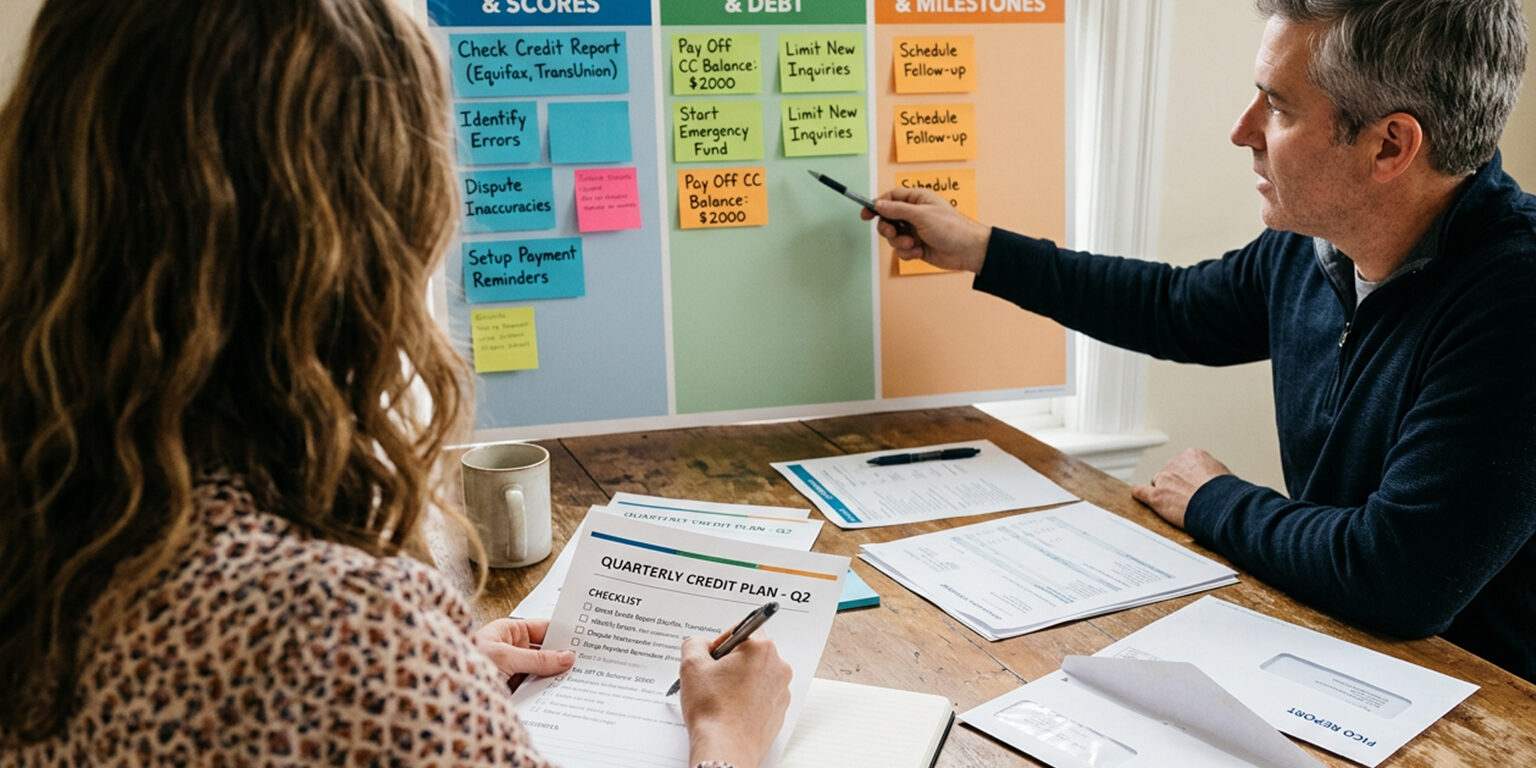
Begin with a clear plan that turns vague credit goals into concrete tasks you can measure and complete. A three-month framework helps prioritize high-impact moves while limiting disruption to daily life. This approach balances quick fixes with foundational steps that improve score drivers like utilization and payment history. Follow this guide to structure practical actions each month and track measurable progress.
Month One: Comprehensive Credit Audit
Start by ordering your credit reports and reviewing them line by line for errors, outdated items, or accounts you don’t recognize. Dispute any inaccuracies promptly and document communications with bureaus and creditors. Also inventory recurring accounts, due dates, and interest rates to identify immediate savings or consolidation opportunities. This initial audit reduces surprises and creates a baseline to measure improvement.
Use this month to establish reliable record-keeping and set alerts for statements and due dates. A disciplined start makes later optimization simpler and more effective. Keep a concise checklist of disputes and confirmations for reference.
Month Two: Optimize Utilization and Payments
Focus on lowering credit utilization and improving payment timing during month two, as these factors often yield the fastest score gains. Aim to keep balances well below limits, and if needed, prioritize payments toward accounts with the highest utilization ratios. Consider scheduling multiple small payments during the month to keep reported balances low and to demonstrate consistent on-time behavior.
- Pay down highest-utilization cards first.
- Set autopay for at least minimums to avoid late marks.
- Request higher limits only when it won’t trigger hard inquiries.
Small, repeated wins in this month build momentum and show lenders responsible management. Monitoring statements weekly helps catch accidental overspending and prevent missed payments.
Month Three: Build Resilience and Diversify
After stabilizing balances and payments, focus on long-term resilience by diversifying credit types and strengthening history. If appropriate, consider a secured loan or a small installment account to mix credit, but only when you can afford it. Keep older accounts open unless there is a compelling reason to close them, since age matters for scoring models.
Develop a maintenance plan that includes periodic reviews, ongoing monitoring, and guarded use of new credit. Building a steady profile reduces volatility and positions you for better offers when needed.
Conclusion
Follow a quarterly plan to turn scattered credit tasks into a manageable sequence of improvements.
Track your progress with clear records and small, consistent actions.
Over time this measured approach strengthens creditworthiness and financial options.