Improving your credit score doesn’t require radical changes overnight. Small, consistent actions compound into measurable improvements over months. This article outlines strategic, practical steps you can start today and maintain with minimal friction. The aim is to highlight behaviors that affect major scoring factors and reduce common setbacks. These changes are manageable and designed to fit into busy lives.
Understand the Components
Credit scores reflect patterns across a few key areas: payment history, credit utilization, account age, credit mix, and recent inquiries. Knowing which components weigh more in scoring models helps you prioritize effort where it matters most. For many people, timely payments and lower utilization yield the fastest gains, while age and mix take longer to move. Other elements improve more slowly but are still important for long-term stability. Recognizing the relative impact of each area lets you set realistic targets.
Start by reviewing your latest credit report and identify obvious mistakes or forgotten accounts. That baseline directs the tactical choices below and prevents wasted effort. Begin with the easiest fixes first and then layer in more strategic moves.
Strategic Small Steps to Take
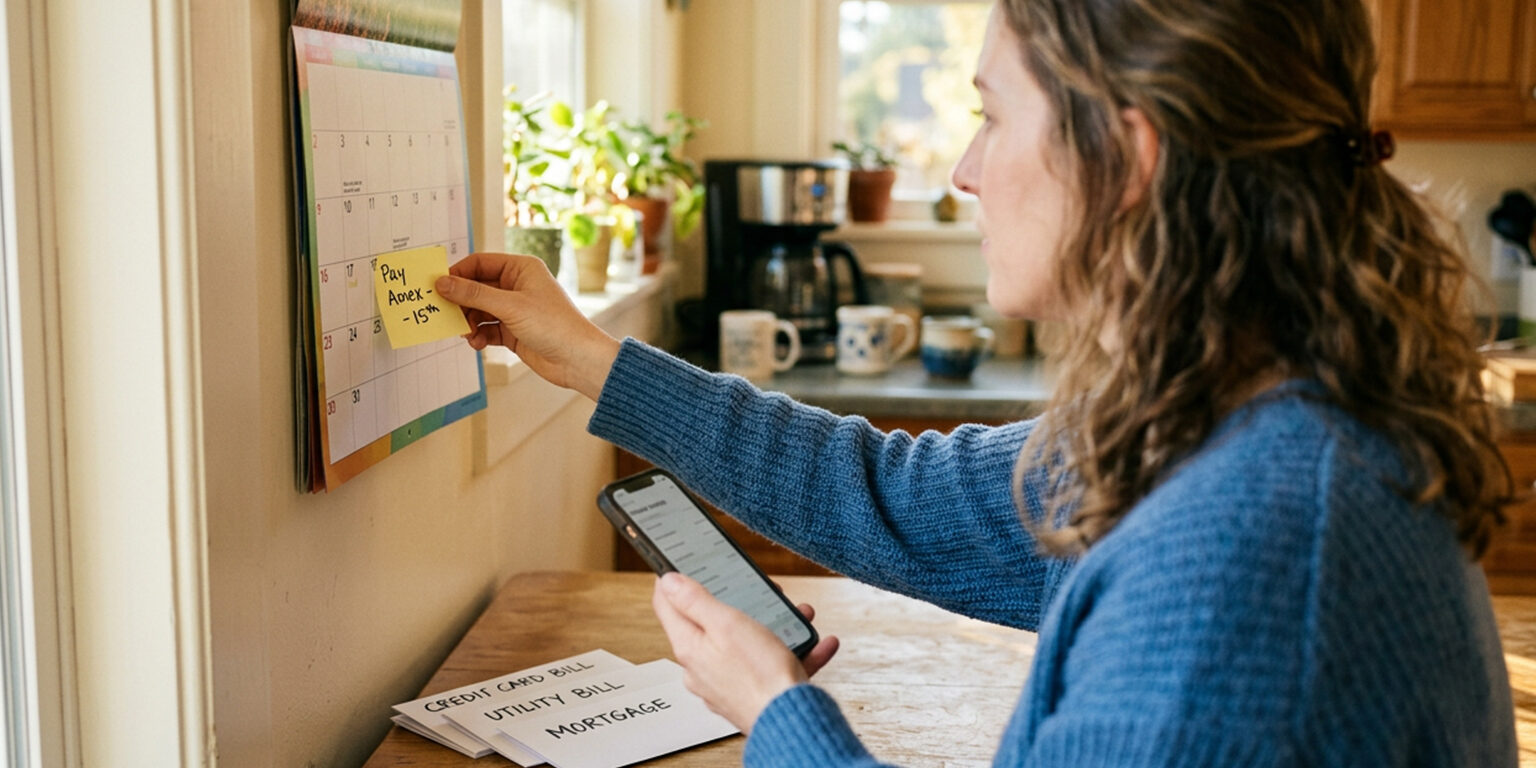
Automate essential payments to avoid late marks and set calendar reminders for any manually paid accounts. Target credit utilization under 30 percent on individual cards, and if possible lower to 10–15 percent for faster impact. Consider small, regular payments ahead of statement dates to reduce reported balances, and request modest credit line increases when responsibly justified. Avoid opening new accounts unless you have a clear short-term need; every application creates a hard inquiry. Use payment strategies like splitting large payments when a single balance spike risks your utilization.
- Automate minimum payments and add extra toward the highest-rate balances.
- Check statement dates and pay down balances before reporting occurs.
- Keep older accounts open unless there’s a compelling reason to close them.
These modest adjustments require little daily effort but address the largest scoring factors. Consistency is the multiplier for measurable progress. Small wins build credibility with lenders over time.
Monitor, Correct, and Adapt
Check your credit reports periodically to spot errors, outdated accounts, or identity issues that hurt your score. When you find inaccuracies, file disputes with the reporting agency and follow up until resolved, keeping records of your communications. Use alerts or a simple spreadsheet to track balances and payment dates instead of checking obsessively, and set concrete monthly goals for utilization and payment success. If a particular strategy stalls—such as a plateau in score—reassess by focusing on age and mix strategies rather than chasing rapid new credit.
Monitoring keeps small problems from turning into larger setbacks and helps you measure progress. Adapting to your score’s response prevents unnecessary churn and wasted effort. Regular review also reduces stress by keeping credit health manageable.
Conclusion
Small, strategic moves compounded over time create meaningful credit improvement. Prioritize timely payments, lower utilization, and regular monitoring to maintain momentum. With patience and consistency, your credit profile will reflect the effort.