Start with a simple purpose: make each card in your wallet perform a clear job. Track typical monthly spending to see where rewards, protections, or low rates will actually matter. Establishing a reliable routine reduces fees and prevents impulse switching. Small, repeatable rules often yield better outcomes than chasing the latest offer.
Assess Your Monthly Spending
Begin by categorizing your regular outflows into a handful of buckets: essentials, commuting, groceries, recurring subscriptions, and discretionary spending. Review three months of statements to confirm patterns and identify where you already spend the most. This evidence-based view helps you prioritize which card features—cash back, category bonuses, or statement credits—will deliver real value. It also highlights rare or seasonal expenses that might justify a specialized card.
When you match cards to actual spend, you avoid unnecessary overlapping features. That clarity makes everyday decisions faster and keeps the wallet lean. Over time, you can adjust roles as life changes without overcomplicating the setup.
Assign Cards to Specific Roles
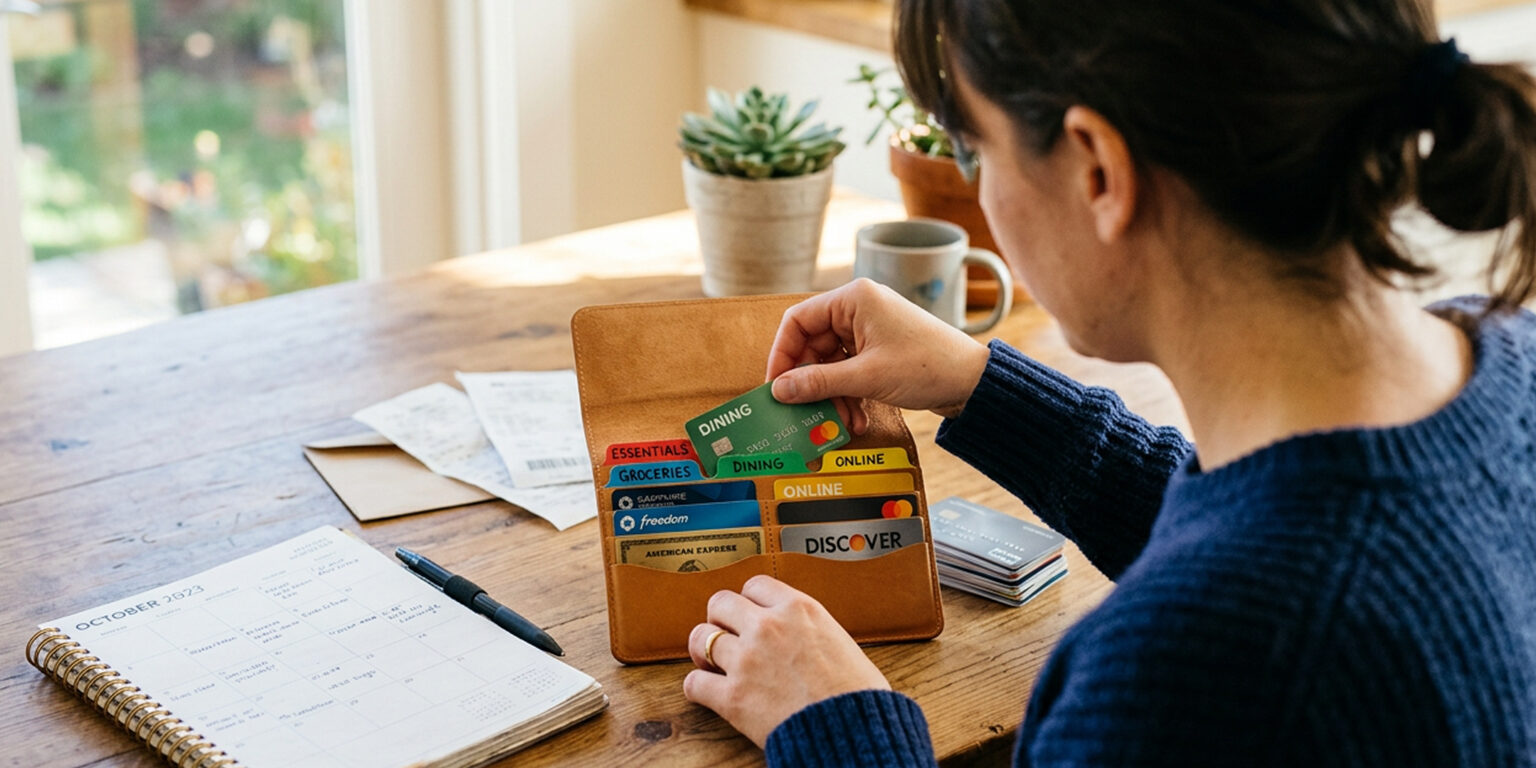
Define a small set of roles that cover your needs: primary everyday card for top categories, a fee-free backup for emergencies, a low-rate or balance-transfer option for larger purchases, and a travel or protection-focused card if you travel often. Limit yourself to three to five active accounts so monitoring and payments stay manageable. Keep a quick reference—digital or physical—with which card to use for each category to avoid missed rewards.
Explicit roles reduce decision fatigue and cut the temptation to carry unnecessary accounts. They also make it easier to evaluate new offers against a clear checklist rather than impulse.
Control Costs and Protect Credit Health
Prioritize cards with annual fees only when the benefits clearly exceed the cost for your spending pattern. Use autopay and calendar reminders to avoid late fees and protect your score, and monitor utilization across accounts to keep balances well below limits. Consider periodic account consolidation if unused cards offer no benefit, but weigh the potential impact on average account age before closing. Regularly review billing cycles and statement dates to time payments and maximize float without incurring interest.
Simple governance—monthly checks and a handful of rules—safeguards both rewards and credit standing. Treat card management as an ongoing habit, not a one-time setup.
Conclusion
Create clear roles, match cards to real spending, and limit accounts to what you can manage. Maintain a short routine for payments and reviews to protect rewards and scores. Small, consistent habits produce steady, practical gains over time.