Improving a credit score can feel overwhelming, but small, focused weekly actions create measurable momentum. Establishing a simple routine reduces missed payments and helps you make strategic adjustments before small issues grow. This article outlines an actionable weekly plan you can follow without drastic lifestyle changes. Follow these steps consistently and review progress regularly to maintain steady improvement.
Assess Your Current Credit Standing
Begin each week by reviewing your credit reports and the most recent score snapshot from a reliable source. Look for errors, unfamiliar accounts, and recent hard inquiries that you didn’t authorize. Note your on-time payment rate and revolving utilization so you know which areas need the most attention. This focused assessment helps prioritize actions that have the biggest short-term impact.
Keep a running log of changes and disputes you file so follow-ups are easy. Regular reviewing prevents surprises when you apply for new credit or a loan.
Weekly Actions That Move the Needle
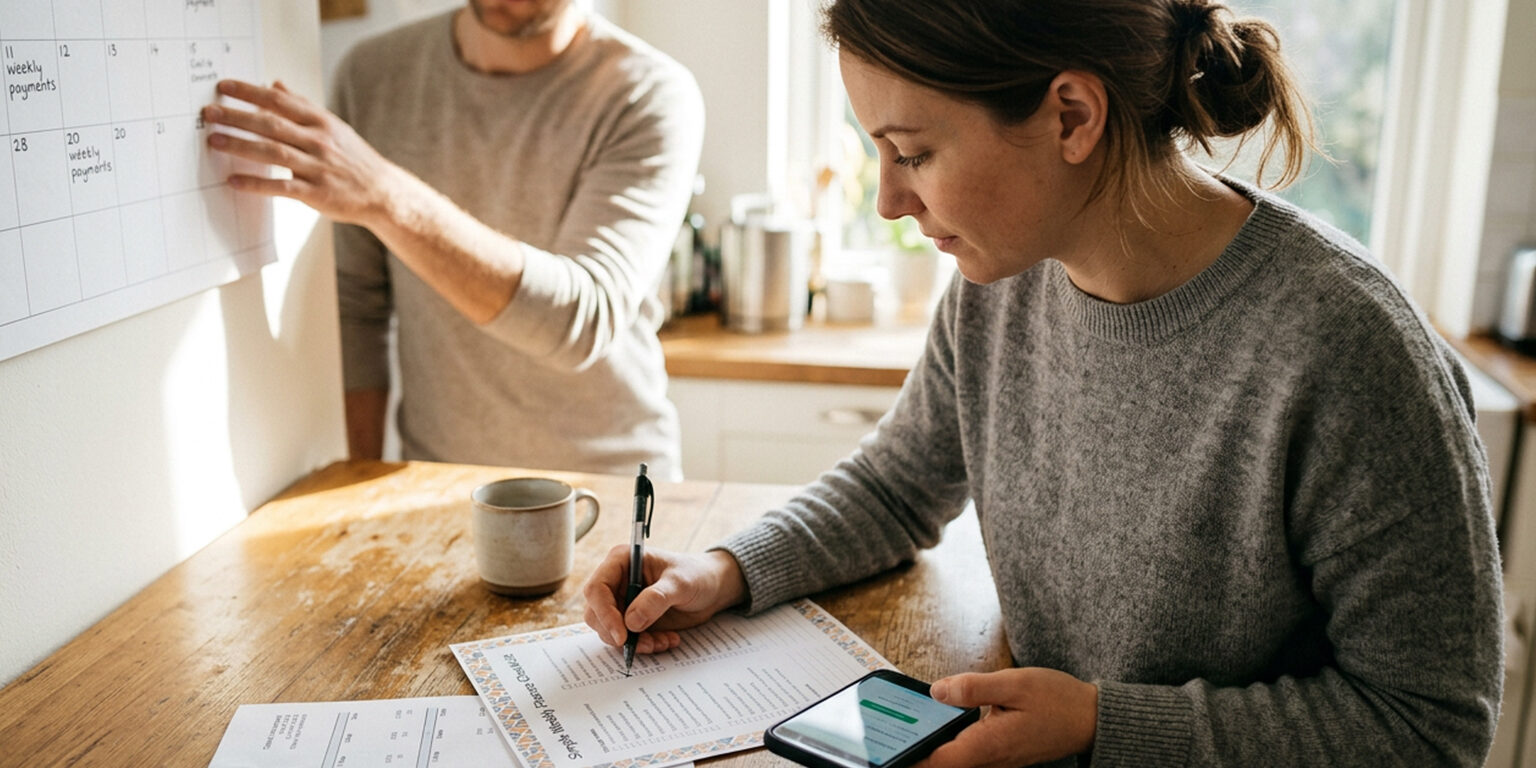
Designate a specific day for practical tasks: pay bills that are due, transfer funds to keep balances low, and schedule upcoming payments. Aim to reduce credit card utilization below 30% across accounts, and preferably under 10% for faster score gains. If balances are high, make at least the minimums plus an extra amount targeted to the highest-interest or most-used card. Consistent small payments reduce interest accumulation and show reliable account management.
- Set calendar reminders for payments.
- Make small additional payments toward revolving balances.
- Consider balance-transfer or consolidation options only after research.
These weekly habits build a pattern of reliability lenders notice. Small, repeated efforts compound into clearer improvements over months.
Handling Common Setbacks
If you notice a late payment or an unexpected account on your report, act quickly to address it. Contact the creditor to clarify the situation and request goodwill adjustments for isolated late payments, and file disputes for true inaccuracies. If you’re facing broader financial stress, proactively create a prioritized repayment plan and communicate with lenders to explore hardship options.
Addressing setbacks early prevents long-term damage and preserves options. A prompt, documented response often produces faster corrections than waiting.
Conclusion
Stick to a short, consistent weekly routine and monitor results closely. Small, deliberate actions reduce risk and gradually improve creditworthiness. Over time this approach creates reliable credit strength and more financial options.