Credit cards can be powerful tools when each card has a defined role in your wallet. Clarifying purpose prevents overlap, reduces fees, and focuses reward accumulation. A small, deliberate set of cards often delivers more value than a large unmanaged assortment. This article outlines practical steps to set roles and streamline monthly credit management.
Define Clear Roles for Each Card
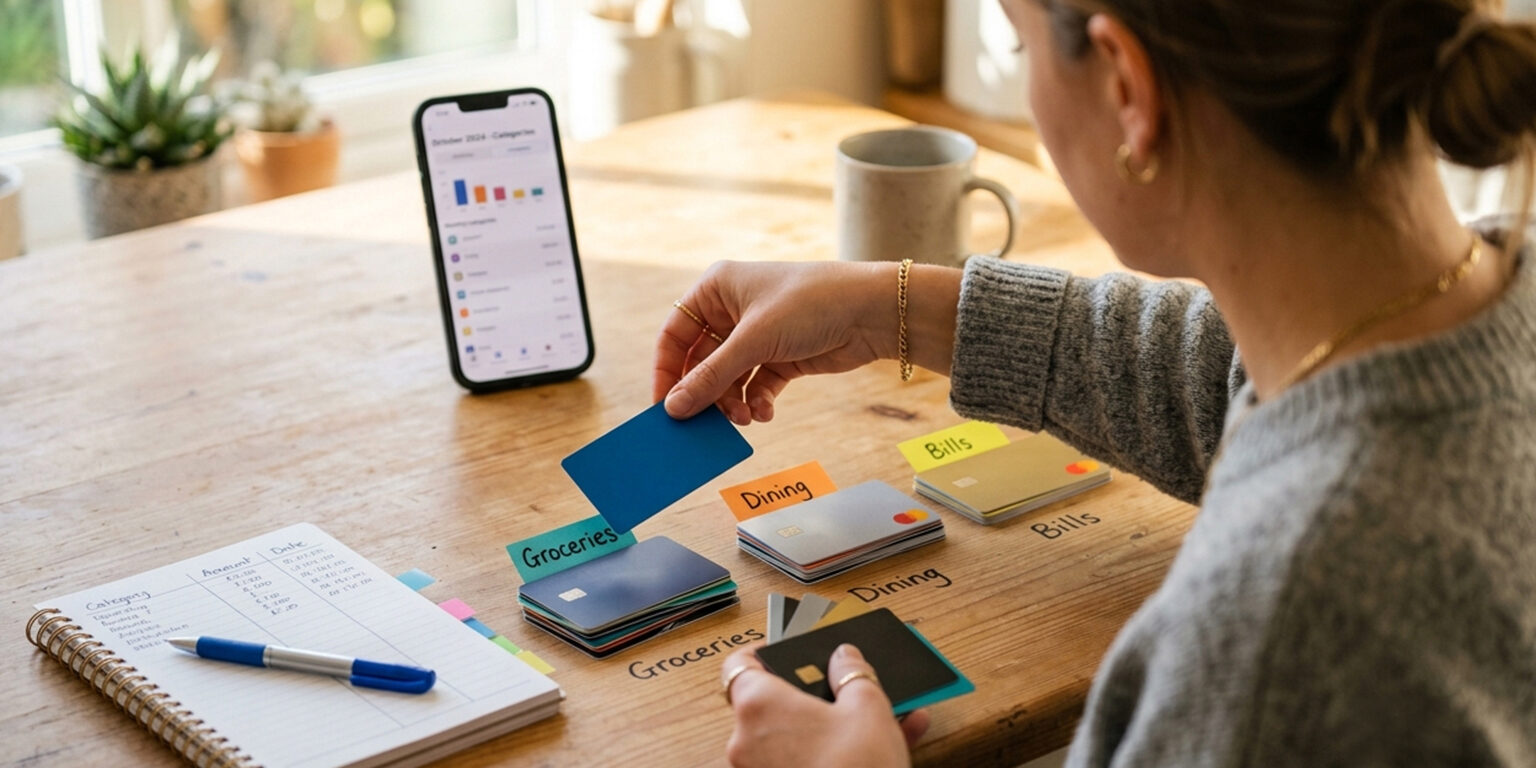
Start by assigning a primary purpose to every card you keep. Choose a spending category, a recurring bill, or a travel style as that purpose so you know when to use it. Prioritize one card for everyday purchases, another for bills or business expenses, and a backup for emergencies. When roles are explicit, it’s easier to track benefits, annual fees, and retention value.
Label cards in your wallet app or a simple note to avoid confusion. The habit of role-based use reduces accidental fee accrual and lost rewards.
Match Cards to Regular Spending
Map your highest-value spending to the cards that return the most points or cash in those categories. Pay attention to rotating categories, merchant codes, and whether benefits apply after a minimum spend. Use statement cycles to align billing dates with paydays and avoid late fees. Where possible, consolidate recurring subscriptions onto a single card to simplify reconciliation.
Matching cards to habitual expenses maximizes returns without increasing spending. A focused approach also simplifies month-end bookkeeping.
Keep an Eye on Utilization and Statements
Maintaining healthy credit utilization requires monitoring balances across accounts rather than just one card. If one role draws large monthly charges, spread activity or request a credit limit adjustment to protect scores. Set autopay for at least the minimum to avoid late payments and calendar reminders for statement closing dates. Regularly check statements for unexpected charges that can undermine the value of a card’s role.
Small monitoring routines prevent surprises and preserve credit health. Automation reduces the maintenance burden while keeping control.
Review, Prune, and Adapt Quarterly
Every three months, review whether each card’s role still makes sense and whether its benefits outweigh fees. Close or repurpose cards that no longer contribute, but consider long-term score impacts before canceling. Look for new offers that fill gaps, such as better category coverage or enhanced protections. Maintain a short list of candidate cards for occasional signup bonuses aligned with your spending plan.
A quarterly review keeps your wallet lean and impactful. It also helps capture shifting needs as spending patterns evolve.
Conclusion
Assigning clear roles to credit cards makes monthly finance management simpler and more rewarding. By mapping cards to real expenses, monitoring use, and reviewing periodically, you preserve value and reduce clutter. A disciplined, role-based wallet delivers steady benefits with minimal extra work.