Managing multiple credit cards can feel chaotic without a concise system that matches everyday needs and billing rhythms. A clear workflow helps you reduce fees, capture rewards intentionally, and avoid late payments while keeping administrative effort low. This article outlines practical steps to assign card responsibilities, align them with statement cycles, and automate routine tasks. With a modest upfront setup you can streamline monthly spending and preserve credit health without constant manual oversight.
Assign roles based on predictable spending
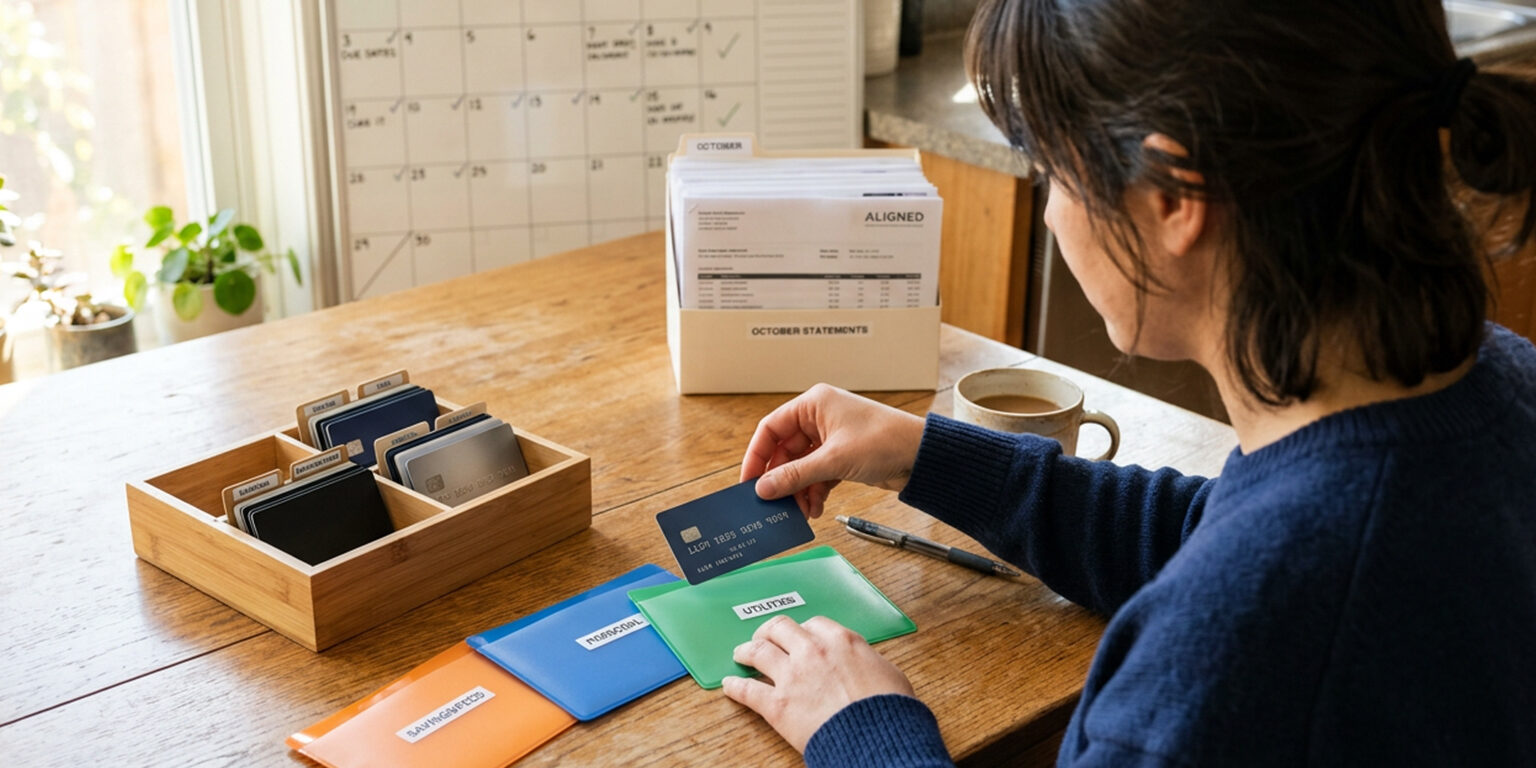
Begin by mapping recurring and high-value expenses to specific cards so each card has a clear, repeatable purpose. Choose one card for essentials like groceries and utilities, another for travel or dining where you earn bonus rewards, and a backup card for emergencies or unforeseen charges. This reduces decision fatigue and ensures rewards stack where they matter most, rather than being scattered across many small accounts. Keeping roles consistent also simplifies tracking and fraud detection because transactions become easier to categorize.
Assigning roles should be flexible and reviewed periodically to reflect changes in habits or merchant categories. Don’t overload a single card; spread utilization to avoid high credit utilization ratios that can affect scores. A simple two- or three-card setup often balances convenience with reward capture effectively.
Optimize around billing cycles and payment automation
Aligning card use with statement and due dates prevents interest and late fees while maximizing grace periods and promotional offers. When possible, pick cards whose statement closings fall after major paydays so you have predictable cash flow between purchase and payment. Set up automated payments for at least the statement minimum and schedule a secondary automated payment to clear the remaining balance when feasible to avoid accidental carryover. Automations remove the manual step and reduce the chance of missed payments during busy months.
Use calendar alerts or a consolidated payments dashboard to confirm automations are operating correctly and to catch any unusual charges early. Small periodic checks keep the system reliable without adding friction.
Monitor costs, review quarterly, and adjust
Track interest, annual fees, and the net value of earned rewards so you can make rational retention or cancellation decisions. Quarterly reviews let you reassign roles if spending shifts, identify cards that no longer provide net value, and spot opportunities to consolidate or close accounts deliberately. Keep an eye on utilization across accounts rather than single-card balances to preserve credit score stability and borrowing capacity. Regular, brief reviews prevent accumulation of hidden costs and ensure your workflow remains aligned with financial priorities.
When adjusting, prioritize simplicity and predictable value over chasing marginal rewards that complicate the routine. A stable, well-monitored setup compounds benefits over time.
Conclusion
Designing a clear credit card workflow reduces friction, preserves rewards, and minimizes fees through intentional role assignment and automation. Quarterly checks keep the system aligned with evolving spending while maintaining credit health. A compact, repeatable routine delivers steady practical value without constant effort.