Small operators face a long list of risks but limited budgets and time to manage insurance. Choosing a compact but effective set of coverages helps protect operations without creating administrative overhead. This article explains how to assess immediate exposures, identify core policy types, and balance cost with protection. The goal is practical guidance you can apply quickly to clarify priorities and identify gaps. Read on for a structured approach to building a focused insurance program.
Assessing Immediate Exposure
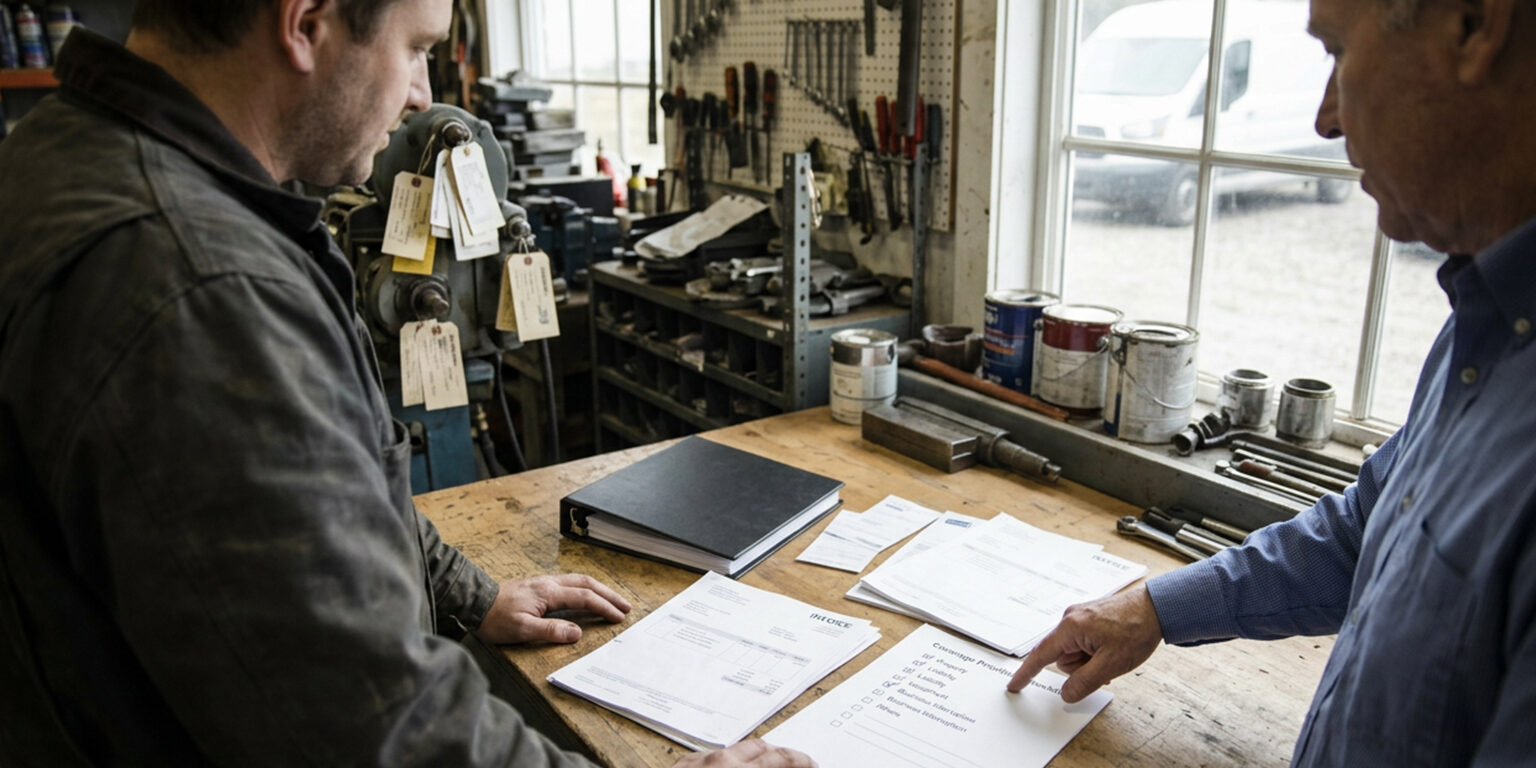
Start by mapping the day-to-day activities that could interrupt revenue or create liability for customers and employees. Look at the highest-frequency incidents and those with the largest financial consequences, such as property damage, customer injury, or professional errors. Gather recent invoices, contracts, and incident reports to quantify typical loss sizes and frequencies. This focused inventory makes it easier to match risks to a limited set of coverages.
Prioritizing exposures reduces the chance of over-insuring less critical risks. It also creates a defensible rationale when discussing options with insurers.
Selecting Core Policy Types
For many small operators a short list of core policies will cover most material risks. Common essentials include general liability for third-party claims, property insurance for owned or leased premises, and commercial auto if vehicles are integral to operations. Professional liability or errors and omissions protection is critical for service providers who give advice or make technical decisions. Workers’ compensation is typically mandatory and protects both employees and the business.
- General liability
- Property insurance
- Commercial auto
- Professional liability / E&O
Choose policies that respond to the prioritized exposures from your assessment. Bundling options or business owner policies can simplify administration while maintaining needed limits.
Managing Cost and Coverage Trade-offs
Small operators must balance premiums, deductibles, and coverage limits to stay protected without draining cash flow. Consider higher deductibles for low-frequency, low-impact exposures and maintain lower deductibles for risks that could shut down operations. Regularly review limits against contract requirements and supplier expectations to avoid surprises when a claim arises. Use endorsements selectively to address gaps rather than buying redundant policies.
A disciplined review schedule and clear documentation help control costs over time. Working with a broker or advisor can speed decisions and reveal cost-effective options.
Conclusion
Clear priorities and a concise set of policies give small operators solid protection without unnecessary complexity. Start with the exposures that threaten revenue and legal obligations, then select core policies to match those risks. Regular review and sensible trade-offs keep coverage aligned with changing operations.