Effective insurance isn’t about buying every policy; it’s about matching limited resources to the functions that keep the business running. Small firms that allocate coverage by criticality improve resilience without overspending. This approach requires a clear map of operational priorities, plausible loss scenarios, and the financial impact of service disruptions. The result is a practical program that supports continuity and strategic decision-making.
Identify Core Functions
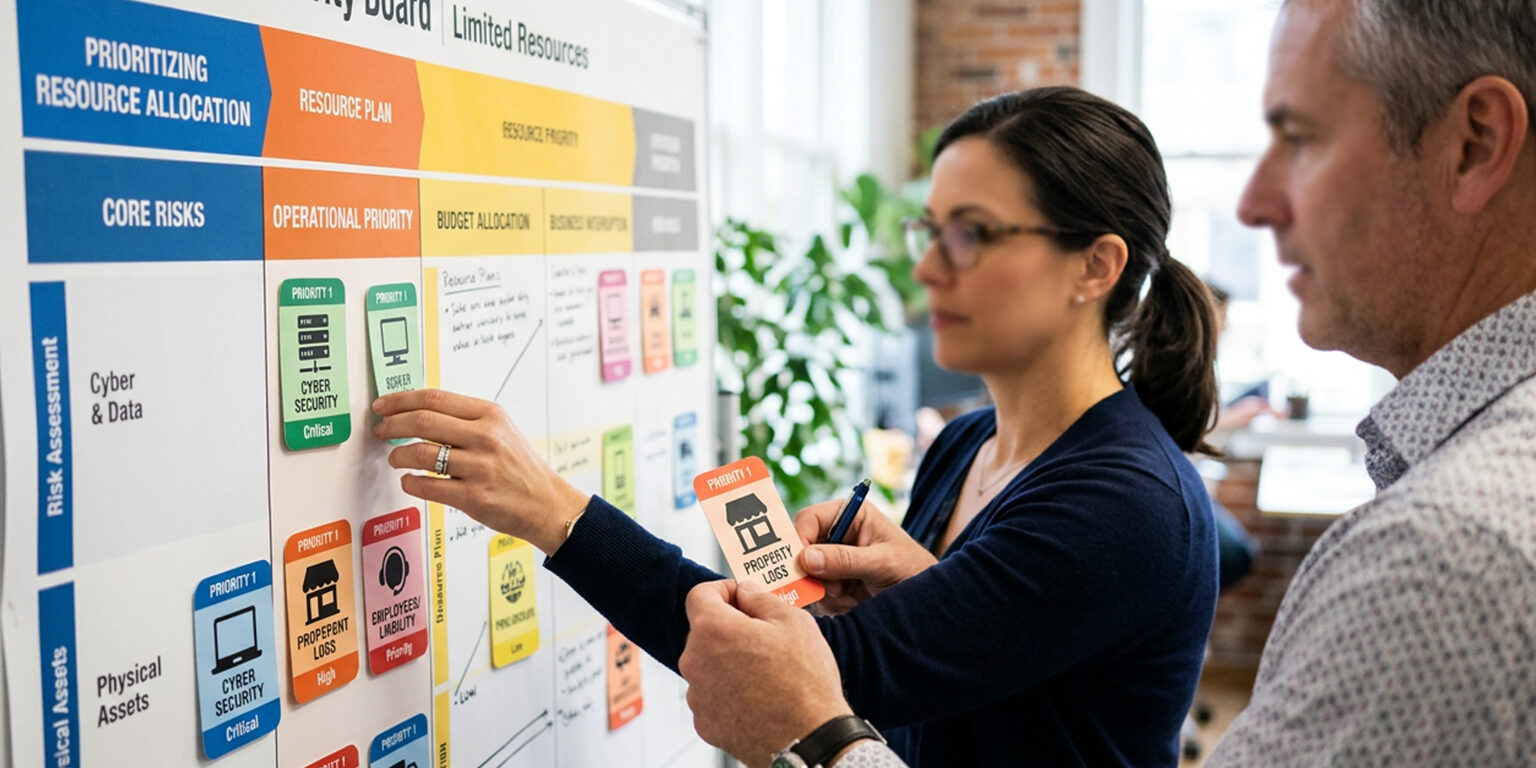
Begin by listing the business functions that directly generate revenue or protect reputation, such as client delivery, IT systems, and customer service. Assess how long each function can tolerate interruption and the downstream costs of downtime. Prioritize functions by combining likelihood of a disrupting event with potential financial and operational impact. This prioritization becomes the backbone of insurance allocation and incident response planning.
- Client-facing operations (revenue impact)
- Key IT and data systems (continuity and compliance)
- Physical assets and premises (safety and access)
Once core functions are ranked, translate those priorities into coverage categories to evaluate exposure gaps and overlaps. Use the ranking to guide which policies get higher limits and which risks can accept cost-sharing.
Match Coverage to Risk Exposure
After prioritizing functions, align specific policies to the risks that threaten each area. For example, cyber insurance should follow IT criticality while business interruption fits operations that cannot pause without severe loss. Look beyond standard package policies to endorsements or standalone solutions that directly protect the highest-priority functions. Regularly update this mapping as services, clients, or delivery methods change.
Work with advisors to quantify exposures where possible and consider scenario modeling to test whether proposed limits and deductibles are sufficient. This evidence-based alignment reduces redundant coverage and highlights where protection is most necessary.
Cost Allocation and Policy Management
With priorities and mappings in place, distribute budgeted insurance spend toward the highest-impact protections first. Use retention strategies, such as higher deductibles or captive arrangements, only where the business can absorb loss without threatening critical functions. Maintain a simple policy inventory and renewal calendar to prevent coverage gaps and ensure timely adjustments as needs evolve.
- Consolidate policies where cost-effective and does not create coverage gaps
- Review limits annually against revenue and operational changes
- Document claims scenarios and past incidents for renewal discussions
Proactive policy management keeps the allocation aligned with strategy and preserves cash flow for growth. Clear records also improve bargaining position with insurers at renewal.
Conclusion
Allocating insurance by critical business functions turns protection into a strategic tool rather than a compliance cost. Prioritize, map coverage to exposure, and manage policies actively to preserve both continuity and capital. This focused approach helps small businesses stay resilient while investing in growth.