As small businesses grow, insurance decisions quickly multiply across operations, people, and assets. Prioritizing those choices by function helps leaders allocate limited budget where it reduces the most exposure. A structured approach keeps coverage relevant while supporting strategic objectives and cash flow management. This article lays out practical steps to evaluate priorities and build a repeatable review process.
Why align insurance with business functions
Linking insurance to specific functions — operations, sales, HR, and property — creates clearer accountability and risk visibility. When coverage decisions map to daily activities, it becomes easier to measure impact and spot gaps that matter to revenue or compliance. Functional alignment also simplifies conversations with brokers and underwriters, since requests are tied to observable exposures. For teams, it reduces ambiguity about who owns incident response and policy review.
Making these connections early supports cost-effective choices and better risk transfer. It also helps prioritize spending when premiums compete with other investments.
A practical evaluation framework
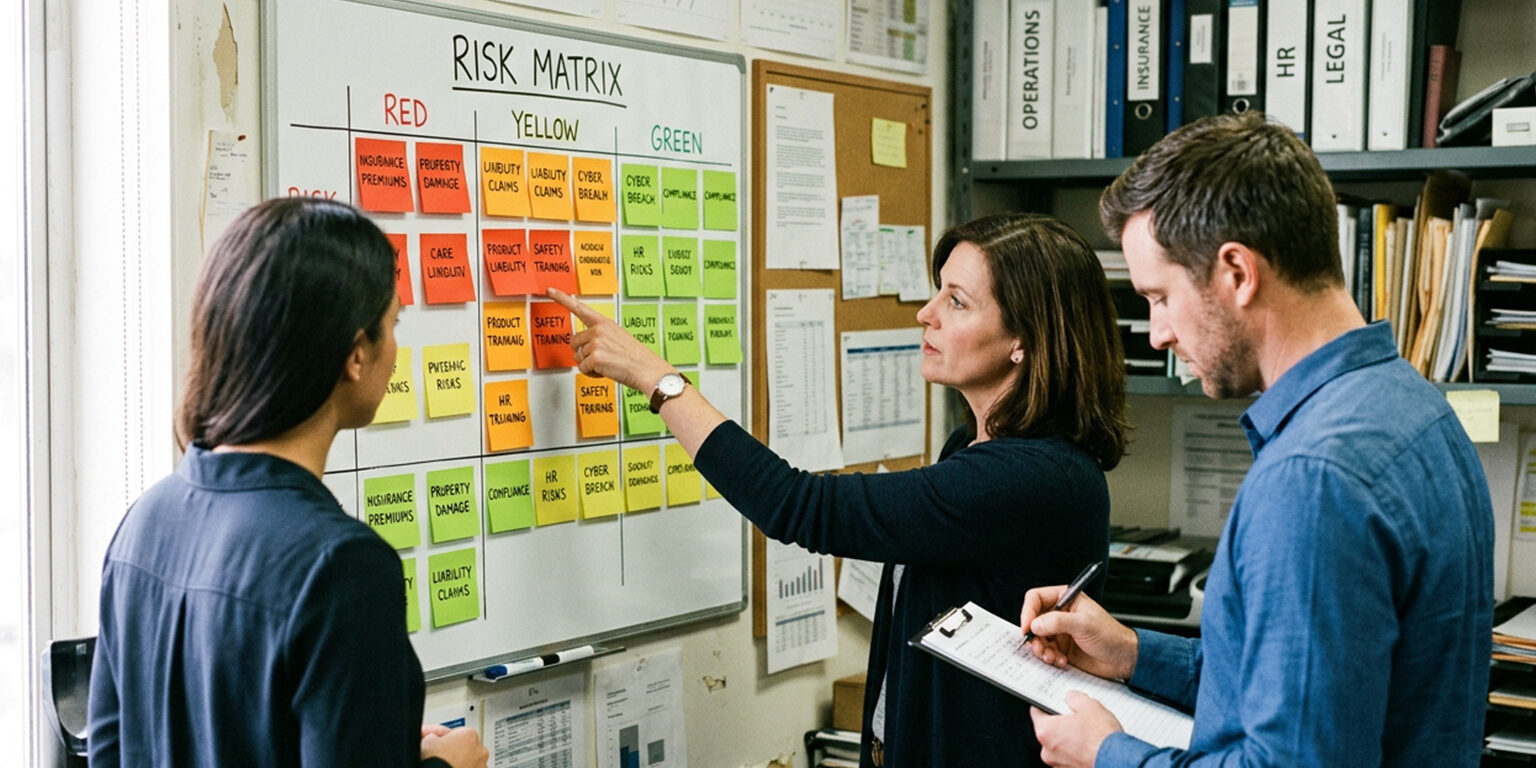
Start by cataloguing core activities and the losses that would most damage each area, then estimate likelihood and magnitude. Use a simple matrix to rank exposures by business impact, not just probability, and identify which require immediate transfer versus tolerance. Factor regulatory obligations, client contractual requirements, and how quickly a loss would interrupt operations. Include contingent risks such as vendor failure and data incidents that cross functional boundaries.
With prioritized risks identified, choose coverages that address high-impact scenarios first and document the rationale for each selection. This creates a defensible record for leadership and simplifies renewals.
Governance, budget and review cadence
Assign clear ownership for insurance governance to a leader who coordinates across functions and the broker. Establish a renewal calendar tied to operational milestones, hiring plans, and contract cycles so limits and endorsements are reviewed in context. Set simple budget rules: protect the most critical functions fully, and apply higher retention where the business can absorb short-term losses. Regular tabletop exercises and claims reviews keep policies practical and ensure endorsements match evolving exposures.
Consistent governance reduces surprises at renewal and helps spread premium increases across planning cycles. It also makes it easier to justify consolidations or specialty placements when growth or new services change the risk profile.
Conclusion
Prioritizing insurance by function focuses resources where interruptions and liabilities would matter most. A structured framework and clear governance help small businesses keep coverage aligned with strategy. Regular reviews ensure protection evolves as the business grows and changes.