Making insurance decisions that support operational efficiency helps small firms reduce waste and protect continuity. Rather than chasing lowest premiums, leaders can adopt a pragmatic framework that balances protection, cost, and flexibility. Start by mapping operations to likely loss scenarios and prioritize what would halt revenue. The guidance below outlines practical steps to streamline coverage choices. A clear process makes renewals less stressful and claims easier to resolve.
Assess Operational Risks
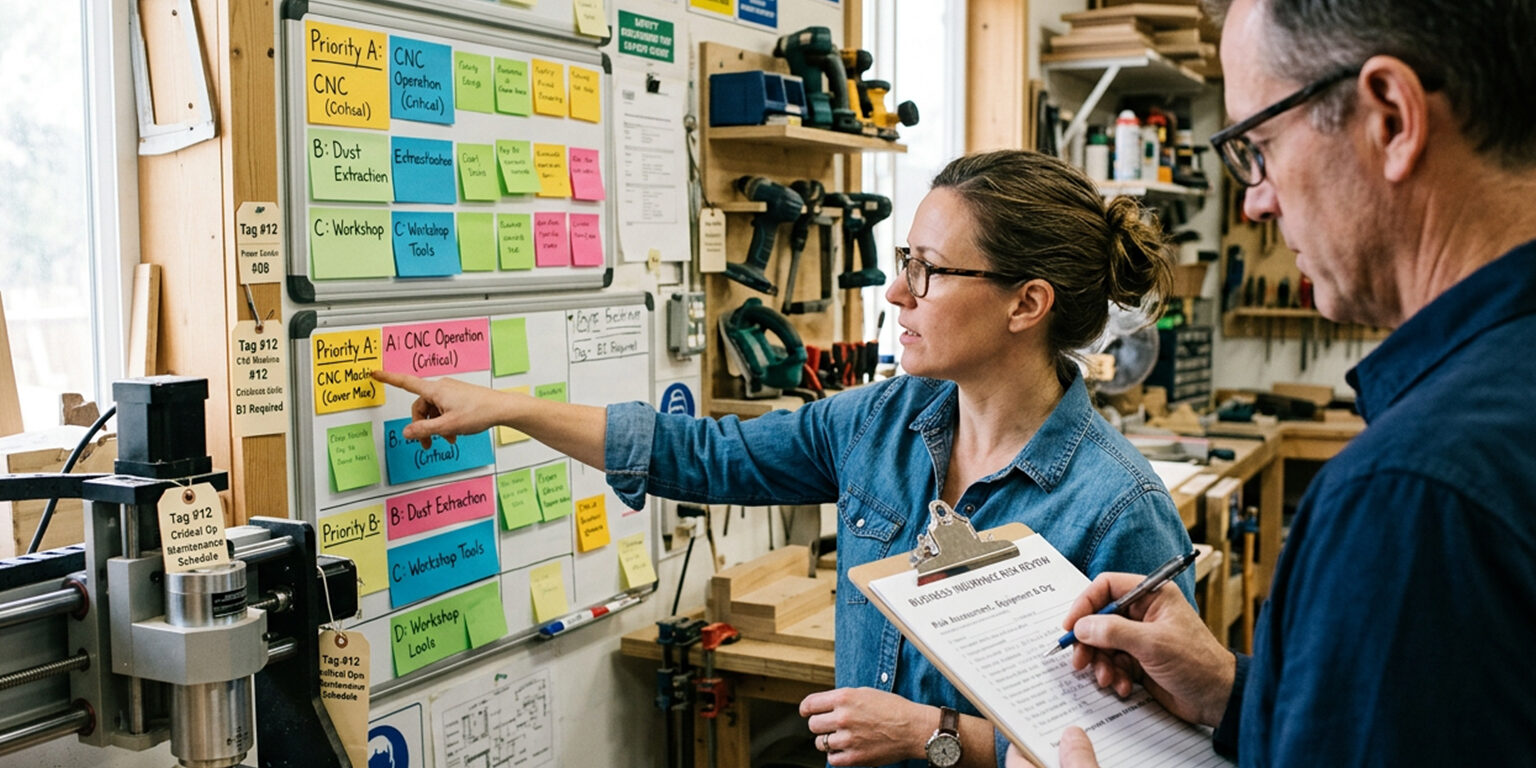
Document core activities, revenue drivers, and assets to see where interruptions would hurt most. Consider both frequency and severity so you can separate routine nuisance claims from catastrophic exposures. Use staff input to capture practical exposure that policy summaries often miss. Where possible, quantify probable losses to compare insurance costs against mitigation expenses.
Rank risks and decide whether to transfer, mitigate, or accept each exposure. That targeted approach prevents paying for coverages that add little operational value.
Prioritize Core Coverages
Start with coverages that protect revenue and legal obligations, typically property, liability, and business interruption when relevant. Tailor limits to realistic worst-case scenarios rather than theoretical maxima. Align deductibles with available cash or credit so a claim does not threaten operations. Also consider contractual requirements from clients or vendors when setting limits.
Begin with minimum acceptable protection and add secondary protections as resources allow. That phased plan keeps premiums manageable while covering the most serious threats.
Leverage Bundles and Endorsements
Bundling policies or adding endorsements reduces administrative friction and can lower overall cost. Seek packages that match your industry to avoid overlapping terms and unclear claims channels. Use endorsements to tweak standard forms instead of buying many standalone policies. Talk to peers in your sector to learn which endorsements are most practical.
- Common bundle benefits: simplified billing, consolidated claims handling, and premium credits.
- Consider endorsements for cyber, hired auto, or equipment breakdown where exposure exists.
Review bundle fine print to confirm there are no gaps for your top risks. Clear documentation of inclusions prevents surprises at claim time. Keep a copy of policy schedules where key terms are visible.
Review and Monitor Regularly
Set an annual review and trigger-based reassessment after major operational changes. Monitor claims trends, vendor shifts, and regulatory updates so new exposures are detected early. Use renewal time to compare options rather than accepting automatic increases. Document observations and decisions to streamline future renewals.
Assign a single owner for the insurance program to maintain continuity and ensure follow-through. Regular small adjustments are far cheaper than one large correction after a lapse.
Conclusion
Streamlining coverage choices means focusing on the exposures that matter most to operations and cash flow. Use risk ranking, prioritized coverages, and careful bundling to balance protection and cost. Regular reviews ensure the program continues to match business realities.