Improving a credit score is rarely about one dramatic move and more about consistent, small choices. Regular payment behavior, thoughtful account management, and strategic planning combine to create steady progress. This article outlines concrete habits you can adopt and sustain without major disruption to your daily life. Read on for practical steps and an adaptable routine to support long-term credit health.
Why steady habits matter for credit
Credit scoring models reward predictability and responsible use over time. Timely payments, low balances relative to limits, and a mix of account types show lenders you manage credit responsibly. Abrupt changes or inconsistent patterns can signal risk and slow improvement. Understanding the elements that influence scores makes it easier to prioritize efforts that yield the biggest impact.
Focusing on daily and monthly routines reduces mistakes and makes positive behavior automatic. Small wins compound, helping establish a reliable credit history without drastic lifestyle changes.
Prioritizing payments and due dates
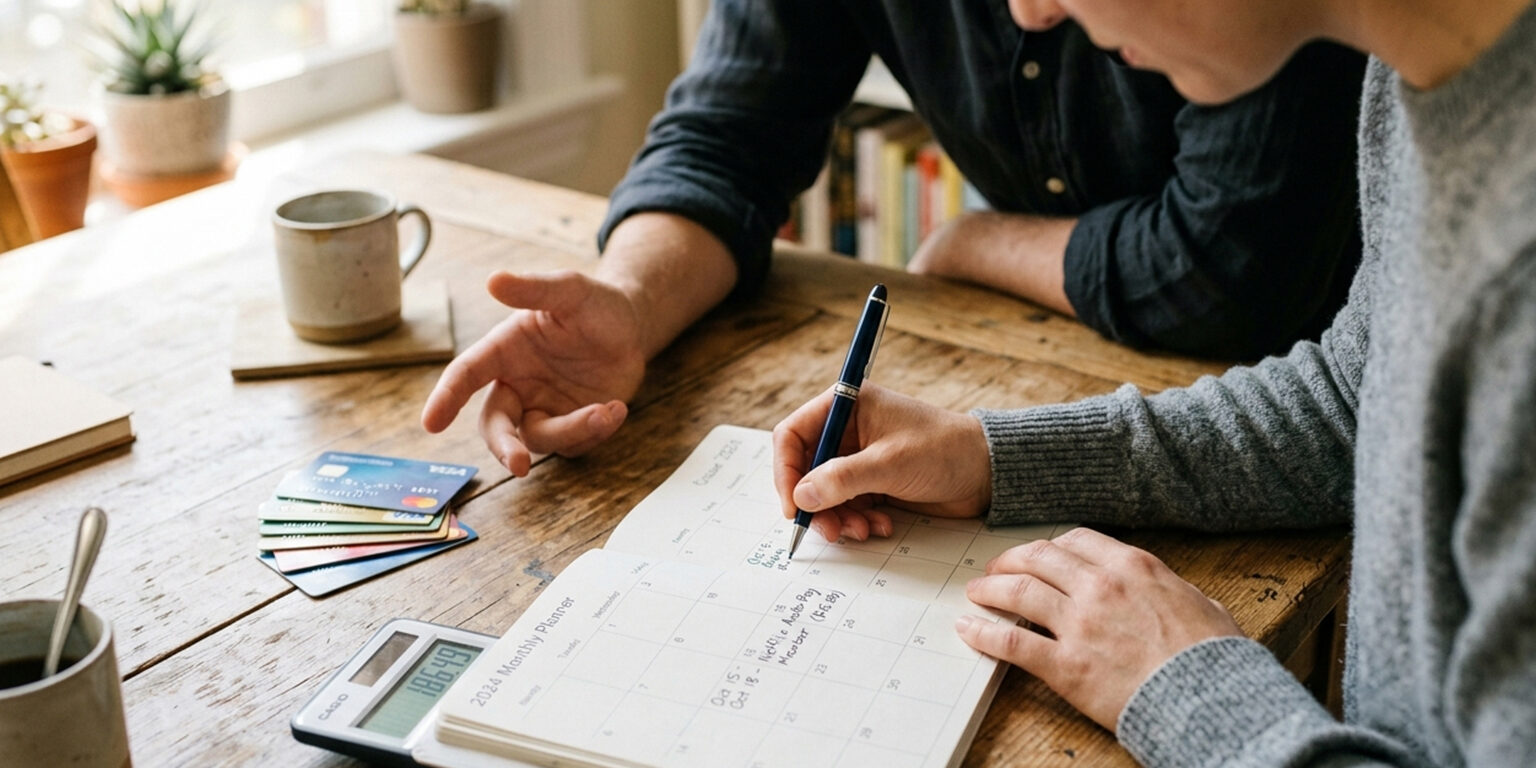
On-time payment history is the most influential factor in many credit assessments. Set up calendar reminders, automate minimum payments, and schedule an extra payment when cash flow allows. If you face a tight month, contacting creditors proactively can prevent missed payments from turning into delinquencies. Consistently avoiding late payments preserves the strongest driver of credit improvement.
Automation and planning remove friction and human error from the process. Regularly review statements to confirm autopay settings and adjust dates to align with pay cycles.
Managing utilization and account activity
Credit utilization — the percentage of available credit you use — directly affects scores. Aim to keep reported balances low by making small mid-cycle payments or spreading purchases across accounts. Avoid closing older accounts solely to reduce complexity, as length of history helps your profile. Thoughtful use of available credit demonstrates restraint and reliability to scoring systems.
Small adjustments to how and when you use cards can lower utilization quickly. Monitor statements to ensure reported balances reflect these management choices.
Monitoring, adjusting, and staying informed
Regular monitoring helps you spot errors, identity theft, or unexpected changes that could harm your score. Review free credit reports periodically and dispute inaccuracies promptly with documentation. Use alerts from your financial accounts to track unusual activity and to remind you of upcoming payments. Staying informed enables timely action and prevents minor issues from becoming larger setbacks.
Make monitoring a simple recurring task so it fits into your routine. Timely adjustments based on what you learn will keep your progress on track.
Conclusion
Small, consistent financial habits build stronger credit over time.
Monitor activity, prioritize on-time payments, and manage utilization closely.
These steady actions compound into measurable improvements and greater borrowing confidence.