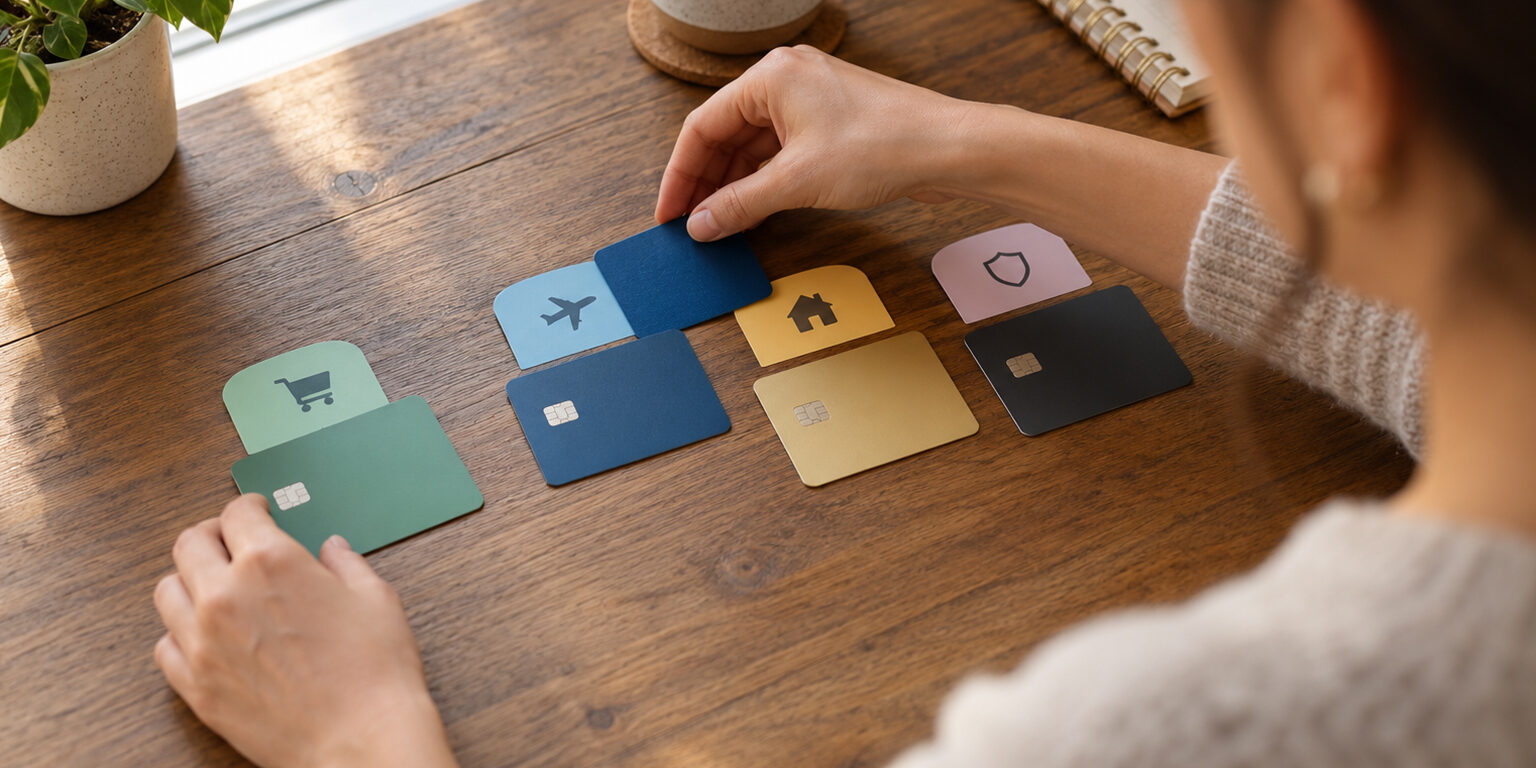
Choosing the right set of credit cards is less about chasing every reward and more about allocating clear roles that reflect real habits. A purpose-driven card map assigns each card to a specific spending bucket, timing, or backup role so decisions become routine. This approach reduces fees, prevents accidental interest, and helps you harvest rewards without adding complexity. The result is a leaner wallet and steadier progress toward financial goals.
Identify your core spending buckets
Start by categorizing monthly expenditures into a few consistent buckets: everyday essentials, recurring bills, travel or dining, and occasional large purchases. For each bucket note where you actually spend, what rewards type benefits you most, and which merchant restrictions apply. Prioritize cards that deliver the highest net benefit after fees and annual credits rather than chasing headline rates. That clarity makes it easier to choose one primary card for each category.
Keep this list simple and update it when habits change. A short list reduces decision friction at checkout.
Match cards to billing cycles and statement dates
Aligning cards with statement cycles and payment dates can smooth cash flow and reduce interest risk. Assign larger recurring payments to a card with a longer float or billing date that matches your pay schedule so you can optimize working capital. Use statement cycles to concentrate bonus spend when pursuing category offers, then pay in full before interest accrues. The administrative effort is small but can meaningfully improve timing and reward capture.
Track due dates in a calendar and set reminders. Small timing adjustments avoid costly mistakes.
Manage utilization and account mix for credit health
Monitor utilization across cards, not just a single account, to keep reported balances low relative to limits. If one card accumulates unavoidable balances, consider shifting discretionary purchases to other cards or arranging small pre-payments before statement closing. Maintain a mix of older accounts and a few newer ones to preserve score diversity and credit age. Remember that closed accounts and unnecessary hard applications can erode benefits over time.
Aim for utilization under common recommended thresholds and avoid churning without purpose. Consistent habits protect both rewards and credit standing.
Regular audits and practical rationalization
Schedule a quarterly review to evaluate which cards are earning, costing, or sitting idle. Canceling or downgrading cards with no role can eliminate fees, but weigh the impact on average account age and available credit. Look for overlapping benefits and consolidate where one card can perform multiple tasks effectively. Treat each change as a small experiment and measure outcomes over a few cycles.
Document decisions and results so you learn what works for your situation. Over time the card map becomes a lightweight framework you can refine.
Conclusion
A purpose-driven card map converts choices into repeatable routines that save time and money. By assigning clear roles, matching timing, managing utilization, and auditing regularly you preserve reward value while maintaining credit health. Start with simple rules and iterate as your needs evolve.