You don’t need a dozen plastic partners to extract value from credit cards.
A small, well-chosen set of accounts can reduce fees, simplify billing, and sharpen rewards.
This piece lays out a practical approach to assigning roles, tracking costs, and protecting your credit.
No jargon, just clear steps to make each card earn its place.
Define Clear Roles
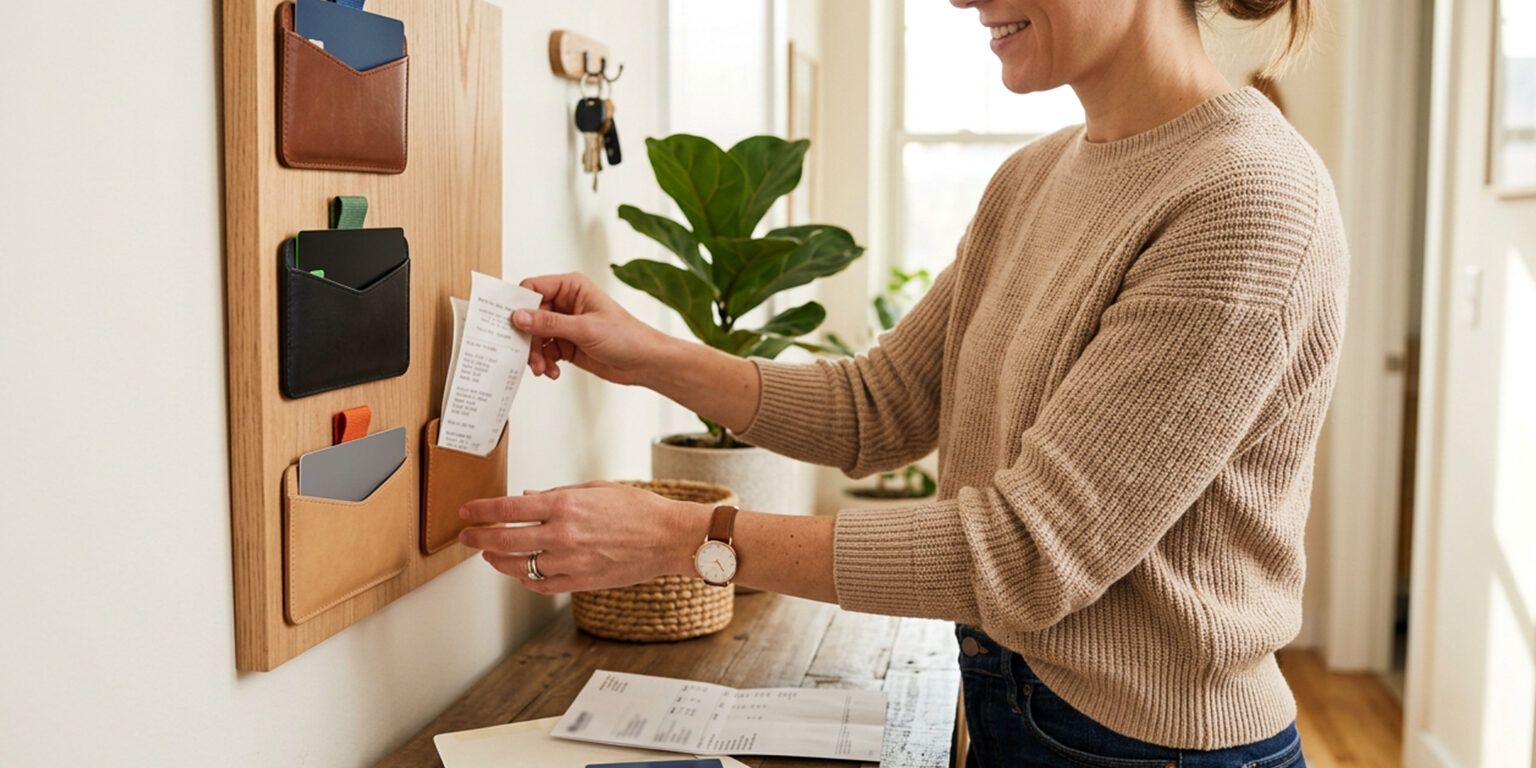
Assigning clear roles cuts decision fatigue and ensures every swipe serves a purpose. Common roles include a primary rewards card for everyday spending, a specialty card for travel or groceries, and a backup card for emergencies. You can also keep a no-fee card for balance transfers or to preserve credit history. Define just three to four roles and resist the urge to chase marginal sign-up bonuses that don’t align with your habits.
Write your roles down and test them for a month. If a card consistently fails to earn its keep, consider replacing or closing it after weighing score impacts.
Match Cards to Monthly Habits
Map regular expenses to the cards that return the most value. Groceries, gas, recurring subscriptions and streaming services often account for the bulk of rewards. Put bills and repeat purchases on cards with highest category bonuses and move occasional buys to general-purpose cards. Use billing cycles and statement dates to time large purchases when needed without crossing payoff windows.
- Rotate cards by category only when the math clearly favors it.
- Track return on cash back as a percentage of spending, not points.
- Set calendar reminders to review sign-up offers and annual fees.
Small changes in where you charge recurring costs make measurable differences in rewards. Keep a short spreadsheet or app to verify the benefits actually materialize.
Protect Score and Control Costs
Rewards disappear if you pay interest or get dinged by fees. Always aim to pay full balances monthly and understand each card’s grace period and fee structure. Maintain low utilization across your accounts by spreading balances and increasing limits only when sensible. Close cards sparingly — the age and available credit they represent can matter more than the extra cash back.
Automate payments and set alerts for approaching limits or billing due dates. Regular mini-audits—quarterly checks of fees, benefits, and authorization holds—keep surprises off your statement.
Conclusion
A compact card lineup built around roles and habits simplifies finances and amplifies returns.
Focus on steady value, low costs, and credit hygiene rather than chasing every new offer.
Small, consistent habits will yield better outcomes than a crowded wallet.