Credit cards can be powerful tools when organized around clear rules that support your monthly budget. A small, consistent system reduces friction, avoids unnecessary fees, and helps rewards contribute to goals. This article lays out practical steps to assign roles, time payments, and evaluate net value without adding complexity. Follow a few steady habits to keep cards working for you rather than against your plan.
Start with a compact strategy that fits existing habits and cash flow. Avoid frequent account churn and focus on predictable benefits that align with regular spending. The next sections break the approach into manageable actions you can implement in a single review session each month.
Assign Clear Roles to Each Card
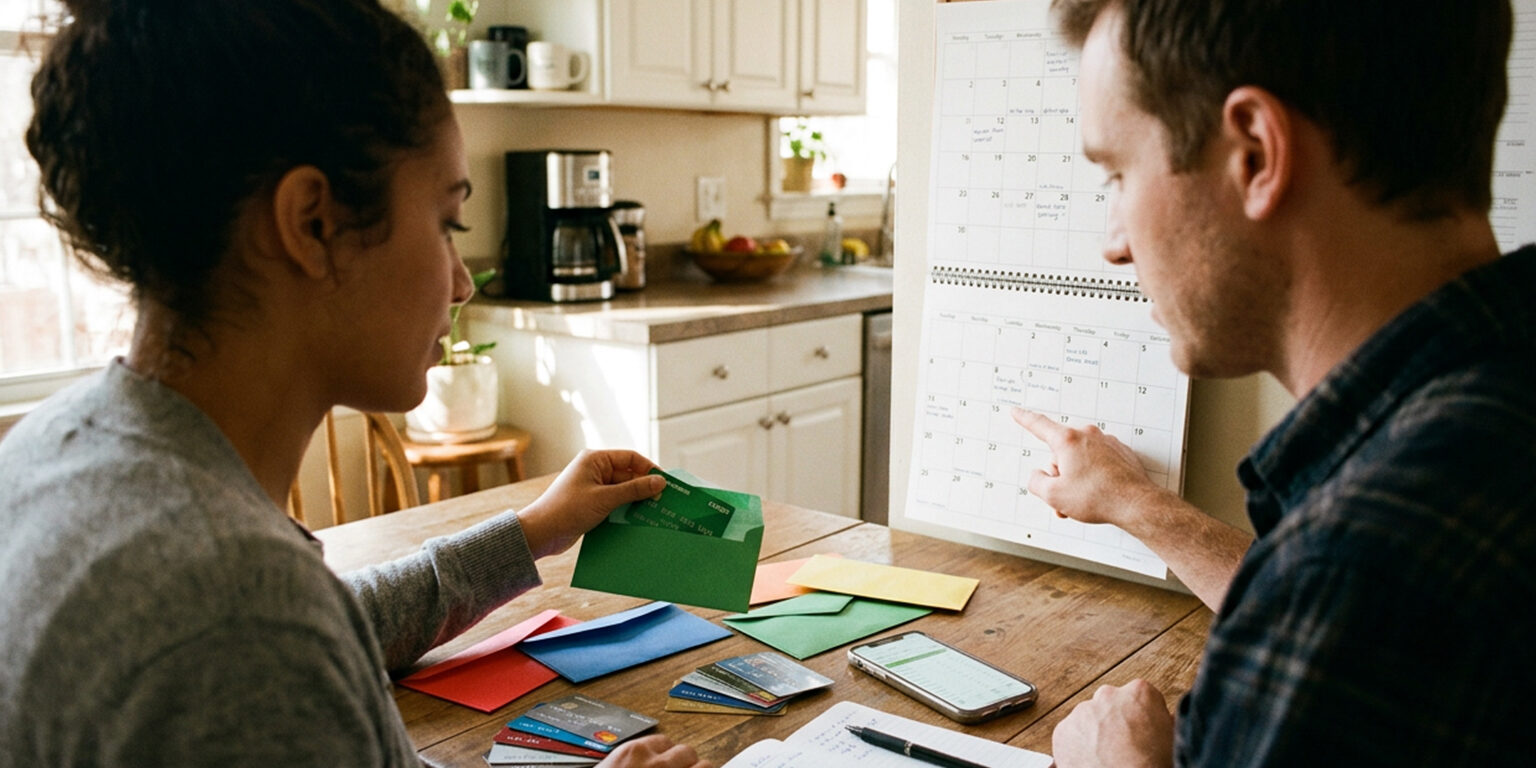
Give each active card a single, prioritized purpose: everyday, travel, business, or backup. When cards have defined roles you reduce decision fatigue and improve reward capture without overspending. Use one card for recurring bills, another for grocery and gas categories, and a third for occasional travel or dining. Keep a debit-like card for low-risk purchases and a premium card reserved for category bonuses.
Document these roles in a note on your phone or a spreadsheet so anyone in the household can follow them. Consistency helps maximize category bonuses and keeps utilization predictable, which supports credit health.
Time Billing Cycles and Payments Strategically
Statement dates and due dates are tools, not annoyances; align them with your cash flow to smooth monthly budgeting. Shift large recurring payments to a statement period that follows payday when possible to avoid short-term liquidity pressure. If you hold several cards, stagger due dates to prevent multiple large outflows on the same day. Always set autopay for at least the minimum to avoid late fees and protect your score.
Review billing cycles quarterly to catch any changes, and adjust autopay or card roles if a cycle change creates friction. Small timing tweaks often improve monthly cash management more than switching cards.
Track Net Value: Fees, Rewards, and Simplicity
Evaluate each card on net benefit: rewards earned minus fees, plus the administrative cost of managing it. High annual fees can be justified if the incremental benefits exceed what a simpler card would provide. If a card requires excessive attention to extract value, its practical benefit may be negative. Use a short monthly check to tally rewards and note any unexpected charges or benefit reductions.
- Calculate average monthly rewards and compare to fee prorations.
- Consider consolidation if multiple cards offer overlapping benefits.
- Keep one no-fee card for emergencies and basic needs.
Prioritize clarity over chasing every bonus; a simpler setup often delivers comparable returns with less risk of missed payments or wasted spend.
Conclusion
Adopt a few simple, purpose-driven rules and align cards to your cash flow and spending habits. Regular, brief reviews will preserve value while keeping complexity low. Over time this approach improves budget stability and frees mental space for other priorities.