Deciding whether to keep, close, or replace a credit card can feel tactical and emotional at once. Small differences in fees, benefits, or utilization can change a card’s net value for your situation. A clear decision framework helps you act intentionally rather than react to a single statement or offer. This article lays out practical criteria to evaluate cards and next steps to manage them responsibly.
Assess the Card’s Ongoing Value
Start by quantifying what you actually get from the card over a year: rewards earned, statement credits, travel protections, and any non-obvious perks. Compare those benefits against annual fees, interest you might pay if balances are carried, and any opportunity cost of a different product. Consider alignment with your regular spending categories and whether the card reduces or complicates your monthly budget. A card that rarely contributes net value is a candidate for change.
Documenting the numbers makes decisions straightforward and repeatable. Run a simple annualized calculation to see which cards are genuinely profitable.
Consider Credit Score and Account Age
Your credit score and the average age of accounts are important non-monetary factors when deciding to close or replace a card. Closing a longtime account may reduce average account age and temporarily affect score, while opening new accounts triggers inquiries and can change utilization ratios. If you have healthy, diverse accounts and a stable history, transitions are less risky. Prioritize options that preserve the most important aspects of your credit profile.
Where possible, time closures or replacements after rewards have been maximized and before large credit applications. That approach reduces unintended short-term impacts.
Balance Fees Against Benefits
An annual fee is not inherently bad; it becomes a problem when benefits don’t offset the cost. Evaluate whether the annual fee buys meaningful conveniences, outsized rewards in your categories, or protections you use. Consider downgrading to a no-fee version of the same issuer to preserve account age while cutting costs. Also review whether similar benefits are duplicated across other cards in your wallet.
If the fee consistently exceeds the value you receive, plan an exit or downgrade with timing that minimizes disruption.
Practical Steps to Replace or Retain
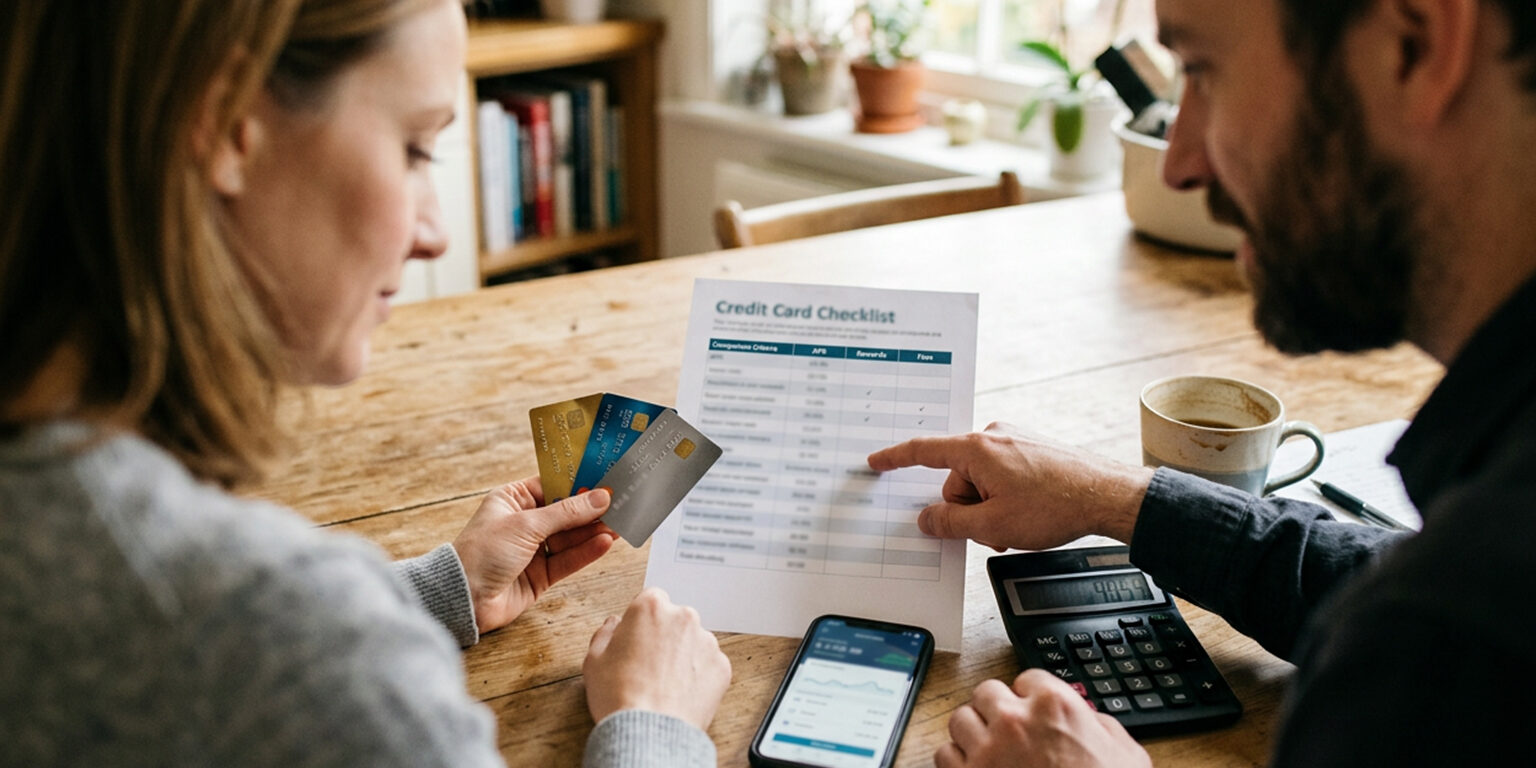
Create a simple checklist before any change: calculate net annual value, note next billing and reward cycles, check impact on utilization and score, and identify replacement options. When replacing, apply only for cards that fill a clear gap in your portfolio rather than chasing bonuses. If keeping, set a periodic review cadence so the card’s role remains aligned with your needs.
- Calculate net benefit annually.
- Consider downgrade over closure when possible.
- Time changes to avoid credit disruptions.
Following a concise routine prevents impulse choices and ensures each card earns its place in your financial plan.
Conclusion
Decisions about cards should balance measurable benefits with credit profile effects and personal convenience. Use a repeatable checklist and time changes to reduce score disruption and maximize value. Regular reviews keep your card portfolio aligned with evolving needs and spending patterns.