A short, consistent monthly review can change how your credit develops over time.
By focusing on small, measurable actions you convert vague intentions into demonstrable progress.
This article lays out a straightforward checklist to set credit goals, monitor key indicators, and respond to issues before they escalate.
Use the steps below to create a reliable monthly routine that supports steady credit improvement.
Why monthly checkups matter
Monthly checkups keep small problems from becoming larger ones and help you spot trends early.
Regular reviews reduce surprises on your credit reports and give you time to correct errors or adjust behaviors.
They also make it easier to celebrate incremental wins, which sustains momentum for longer-term goals.
Scheduling a short, focused review each month requires minimal time but delivers outsized benefits.
Treat it as part of your financial maintenance.
A practical monthly checklist
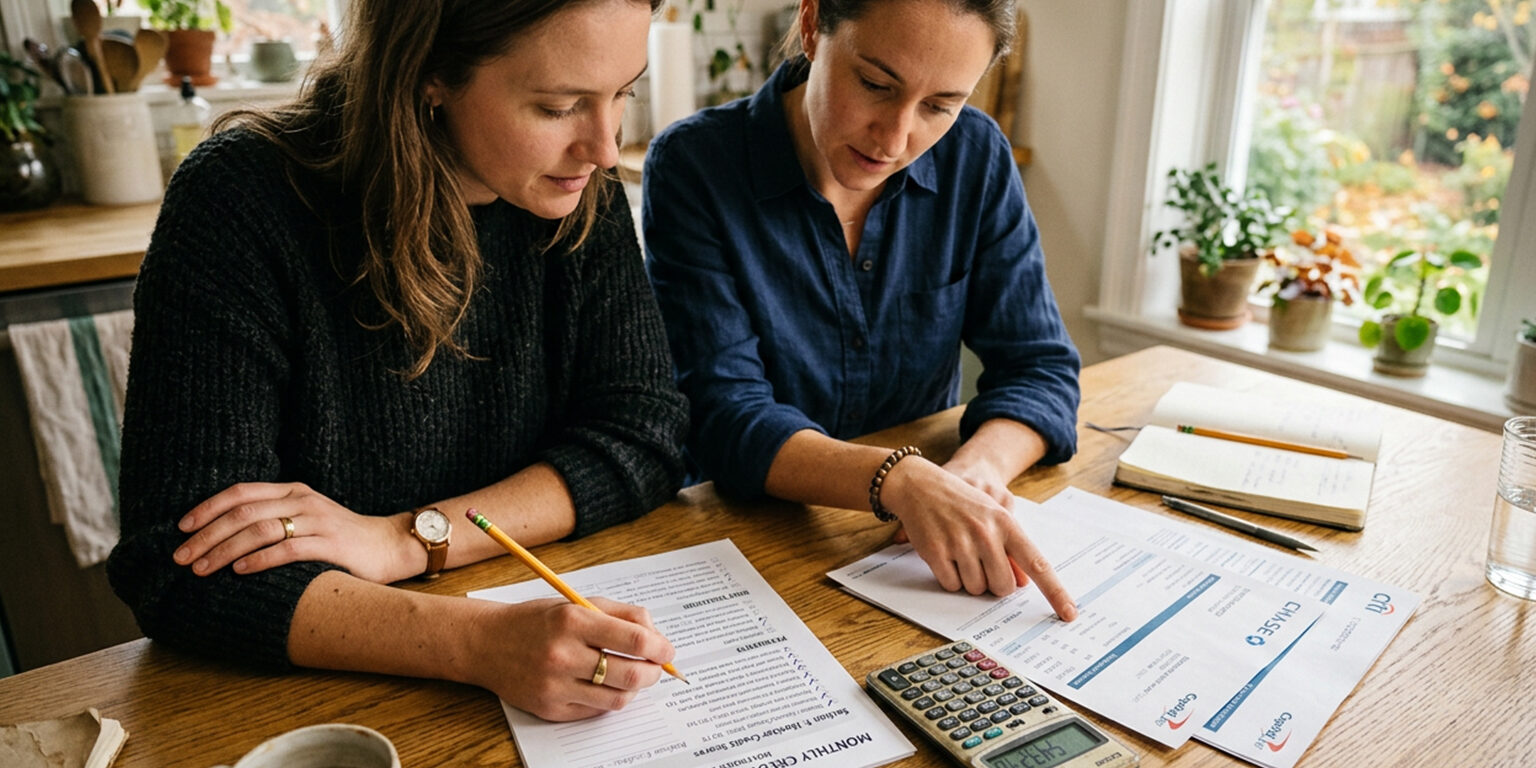
Start by verifying recent account activity and checking for unfamiliar entries.
Confirm current balances, due dates, and whether any payments recently reported late.
Assess your credit utilization and set a target percentage to move toward next month.
Document any disputes opened or resolved and note identity alerts.
- Check recent statements for unauthorized transactions.
- Confirm payment due dates and automatic payments are set.
- Calculate utilization for each major card and overall percentage.
- Review notices from creditors and note any disputes.
- Flag hard inquiries and new accounts for follow-up.
Use the checklist to guide your review and mark items as complete.
Over time you’ll refine priorities that matter most for your score.
Tracking progress and adjusting
Record key metrics each month: balances, utilization, number of accounts in good standing, and any hard inquiries.
Plotting these values creates a simple performance history you can review quarterly.
If a metric moves in the wrong direction, identify the root cause and set a specific corrective action.
Adjust goals to be realistic and time-bound so progress is measurable.
Celebrate milestones and reset targets as you improve.
Setting realistic targets
Break long-term credit aims into monthly and quarterly milestones.
For example, reduce overall utilization by five percentage points over three months by prioritizing payments.
Another target could be avoiding new hard inquiries for a defined window while you refinance or negotiate terms.
Document these targets in your monthly review and assign owners for actions if you share finances.
Small, measurable targets make it easier to track and adjust.
They also help maintain motivation because progress becomes visible.
Conclusion
A disciplined monthly checklist turns abstract credit goals into manageable steps.
Small, consistent actions sustain steady improvement and fewer surprises.
Commit to the routine and revisit your plan as your financial situation changes.