Improving a credit profile doesn’t require sweeping changes; small, deliberate adjustments compound over time to produce measurable results. This article outlines practical routines and mindset shifts that help stabilize credit performance and make scores more resilient. Each recommendation focuses on behaviors you can maintain without dramatic lifestyle changes. Read on for actionable steps you can start this week and sustain long term.
Know the components that matter
Credit scores reflect several distinct factors, and understanding their relative weight helps you prioritize efforts. Payment history, amounts owed, length of credit history, new credit, and credit mix each play a role. Focusing on the highest-impact areas first—typically payment history and utilization—yields the fastest, most reliable improvements. Clarity about these components prevents wasted effort on low-impact tactics.
Begin by reviewing your credit summary so you can target weak spots with confidence. Regular review keeps you focused and less likely to react to single-score fluctuations.
Keep payments predictable
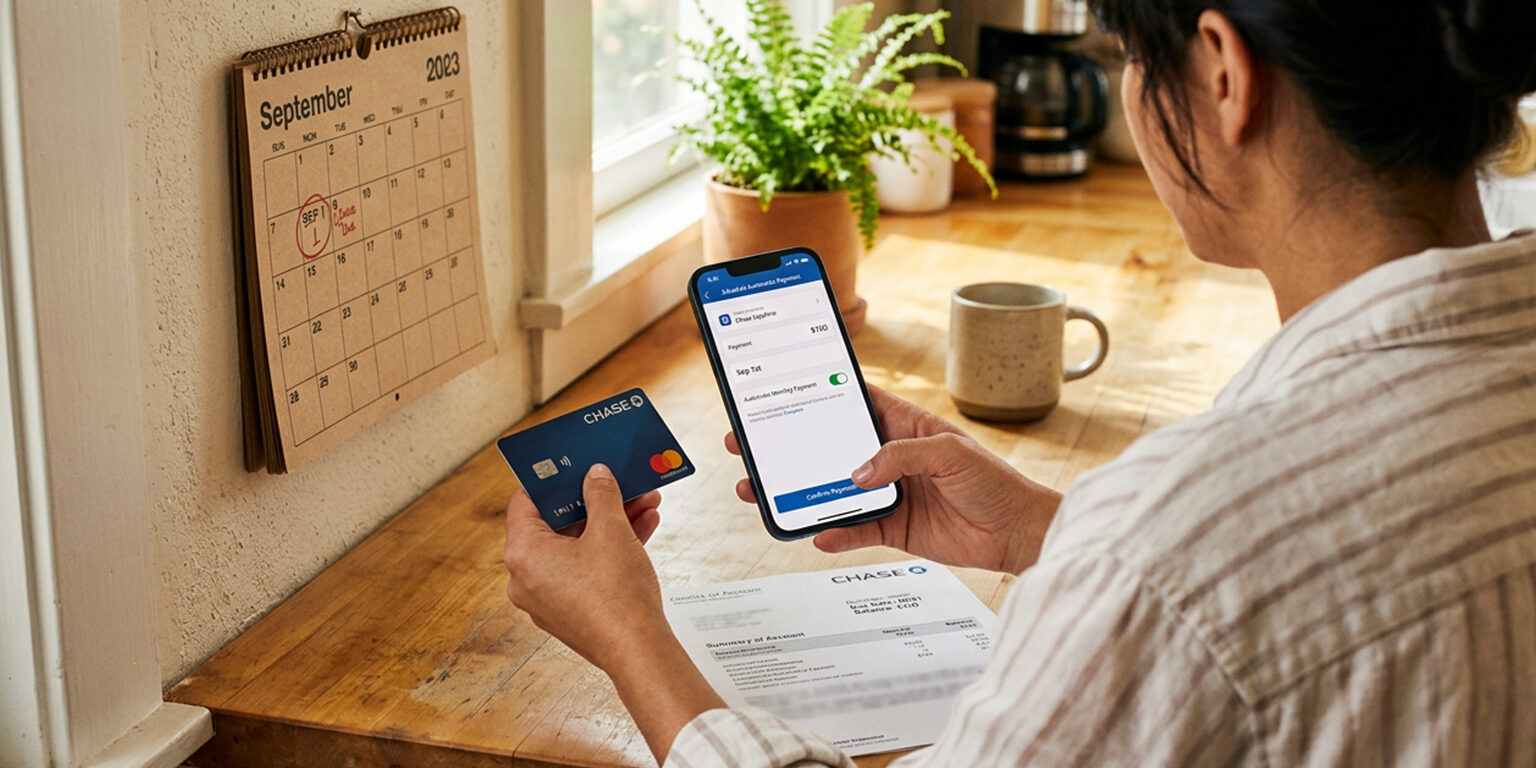
On-time payments are the single most important driver of a healthy credit profile. Automate recurring payments where possible and set calendar reminders for any manual bills. If cash flow varies month to month, prioritize minimum payments to avoid late marks and then allocate extra funds strategically. Even occasional consistency problems can be mitigated by a system that reduces manual steps and human error.
A predictable payment routine reduces stress and preserves the value of your payment history. Over time, consistent payments compound into improved lender confidence and better score behavior.
Control credit utilization and balances
Keeping balances low relative to available limits signals responsible borrowing and helps scores. Aim to keep utilization below recommended thresholds, and spread charges across cards if possible to avoid concentrating balances. Consider small, regular payments during the billing cycle to lower reported balances before statements close. Avoid closing older accounts solely to eliminate temptation, since length of history also matters.
- Track utilization per account and overall.
- Make mid-cycle payments to reduce reported balances.
- Resist large new balances on recently opened accounts.
These habits reduce short-term volatility and create a foundation for steady improvement. Lower utilization often leads to quick positive movement in scoring models.
Review reports and correct errors regularly
Errors on credit reports can suppress scores unnecessarily; periodic review is a simple defense. Check reports at least annually and look for incorrect account statuses, duplicate entries, or identity issues. When you find inaccuracies, follow the appropriate dispute process and keep records of communications. Proactive monitoring also helps you spot early signs of fraud or identity theft.
Maintaining clean, accurate reports prevents avoidable setbacks and supports long-term score gains. Make report review a routine part of your financial calendar.
Conclusion
Small, consistent adjustments across payments, balances, and monitoring build a stronger credit profile over time. Prioritize high-impact actions and automate what you can to reduce friction and errors. With steady application, these practices lead to more reliable credit outcomes and greater financial flexibility.