Consolidating credit cards can simplify your finances and reduce ongoing costs.
Before you close accounts or combine balances, a focused plan helps preserve credit health and maximize value.
This article outlines practical rules to assess accounts, choose which cards to keep, and manage the transition.
Use these steps to create a lean card lineup that fits regular spending and financial goals.
Assess Current Cards
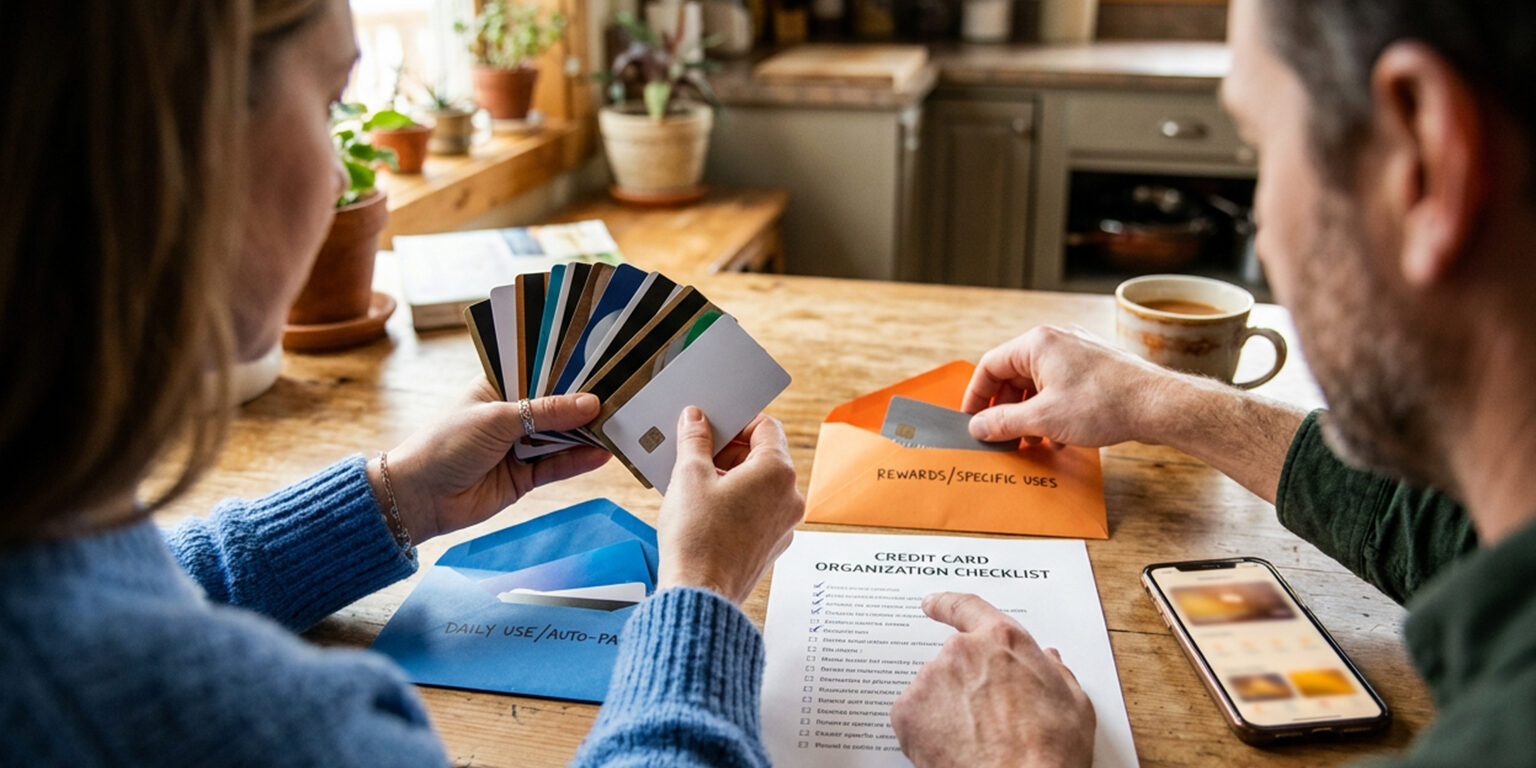
Start by listing every card, its annual fee, rewards structure, interest rates, credit limit, and any active benefits or protections. Note recurring charges tied to specific cards and one-time perks like sign-up bonuses that may still be valid. Identify cards with overlapping rewards or fees that outweigh their benefits, and flag accounts that contribute meaningfully to your overall credit limit. Also check issuer retention offers and whether benefits will disappear if you change usage. Pay special attention to cards with annual fees that are not offset by benefits you actually use.
This inventory creates a clear baseline for consolidation decisions. It reduces surprises during the transition.
Choose Cards to Keep
Aim to retain a small mix of cards that cover your core spending categories while minimizing fees. Prioritize cards that provide durable value such as high earning on everyday categories, strong travel protections if you travel, or low ongoing costs. Consider keeping one card for everyday purchases, one for specific bonus categories, and one as a backup with a long credit history. Avoid holding multiple cards that compete for the same rewards. Also weigh issuer ecosystem value like flexibility of reward transfers.
- High net value after fees
- Useful ongoing protections
- Long credit history / high limit
Simplicity improves use and monitoring, and selecting complementary cards preserves flexibility. Make choices that reduce friction for regular spending. Periodically reassess as promotions and personal spending change.
Transition and Credit Health
When you move balances, prefer a strategy that minimizes interest and preserves available credit — balance transfers can help but watch transfer fees and introductory periods. If you close a card, consider the effect on your average account age and credit utilization; keep the oldest accounts open when possible. Update autopay and billing to avoid missed payments, and monitor your credit report during the process. If a card has a high fee but valuable benefits, negotiate waivers or downgrade before cancelling to maintain credit history. Watch for unexpected charges and update saved card details on merchant sites.
Track changes and give yourself a month to confirm autopay and billing updates. Small administrative checks prevent costly errors. Keep a simple checklist to track steps and dates.
Conclusion
Consolidating thoughtfully reduces complexity without sacrificing value.
Apply a rules-based approach to assess, select, and transition cards.
Regular review keeps your credit lineup aligned with changing needs.