Small businesses face a shifting set of risks as they grow, and an intentional insurance architecture helps translate those threats into manageable protections. Rather than treating policies as static line items, owners can assemble coverage layers that align with operational priorities and cash flow. This article outlines a practical, adaptable approach to identifying exposures, designing scalable policies, and keeping costs predictable. The goal is to help leaders make informed trade-offs while maintaining essential protection.
Understanding Core Exposures
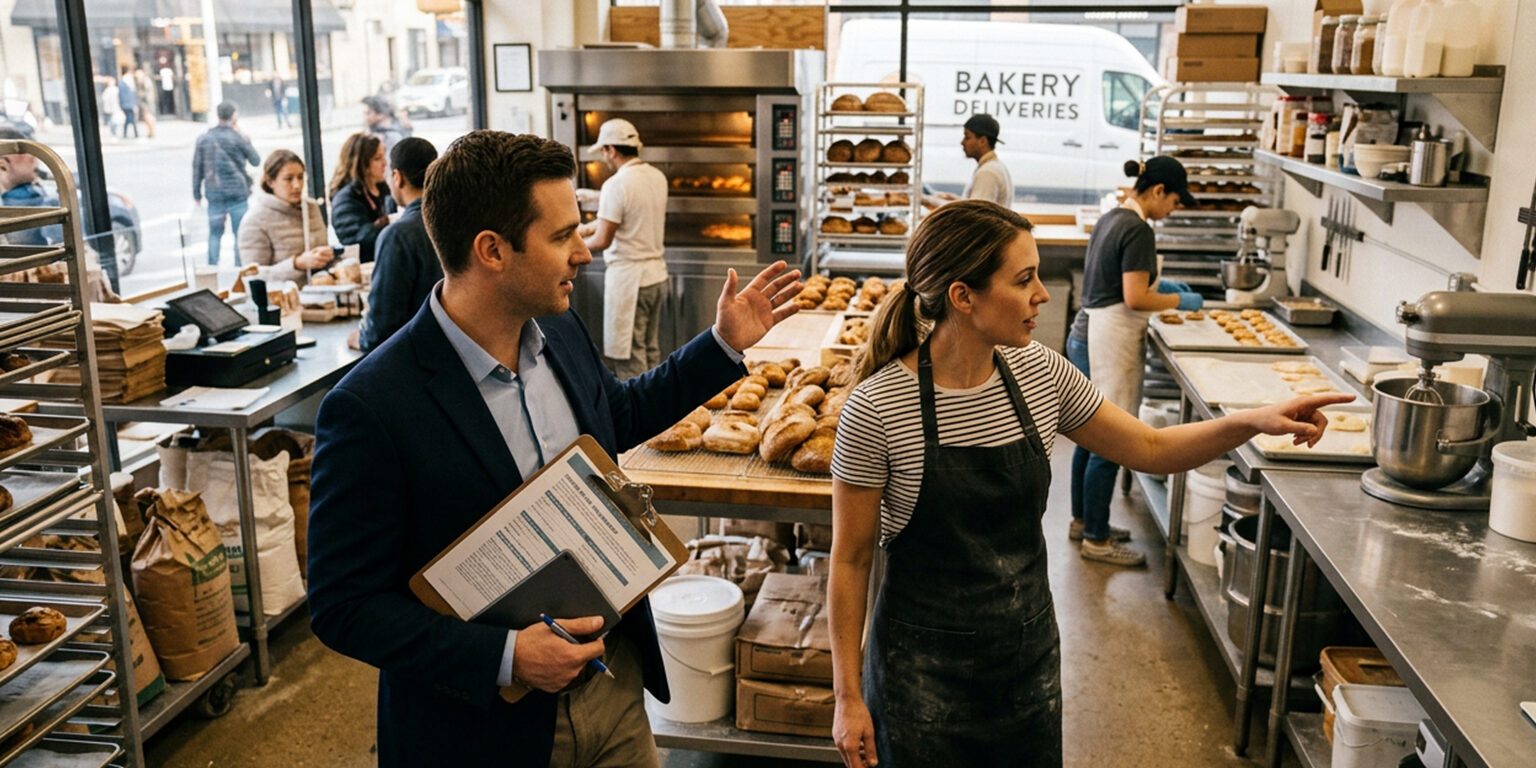
Begin by mapping the activities that create the greatest operational, liability, and property exposures across your business processes. Look at client interactions, supply chain dependencies, employee activities, and the physical or digital assets that would be costly to replace or disrupt. Prioritizing exposures allows you to focus on coverages that materially reduce the risk of catastrophic losses, rather than buying duplicate or unnecessary policies. This targeted assessment also makes conversations with brokers and underwriters more productive and efficient.
Use incident history and near-miss events to refine the exposure map over time. Regular reviews after key changes—new services, locations, or staffing—keep the map current.
Designing Scalable Coverage
Design policies in layers that can expand as revenue and complexity grow: core protection first, then optional excess limits, and specialized endorsements based on emerging needs. Core protection typically addresses general liability, property or business interruption, and workers compensation where applicable. As exposure increases, consider higher limits, cyber liability, professional liability, or tailored endorsements for niche risks. Structuring coverage this way keeps initial costs manageable while allowing predictable scaling as the business matures.
Document triggers for scale-up—revenue thresholds, headcount milestones, or new contractual obligations—so adjustments happen before protection gaps appear.
Controlling Cost Without Sacrificing Protection
Cost control starts with risk management: safer operations and documented controls reduce premiums and broaden insurer appetite. Evaluate deductibles and retention levels deliberately; higher retentions lower premiums but must be affordable when claims occur. Bundle thoughtfully—combining policies with a single carrier can yield discounts, but always weigh coverage breadth and claims service against price. Regularly request competitive quotes and use loss runs to demonstrate strong loss experience during renewals.
Investing in loss prevention and clear contractual risk transfer can improve both protection and cost outcomes over time.
Conclusion
Adopting a coverage architecture rooted in prioritized exposures, scalable layers, and active cost control makes insurance a strategic tool rather than an administrative burden. Regular reviews tied to business milestones keep protection aligned with operations and reduce the chance of surprise gaps. With a clear plan, small businesses can balance protection, flexibility, and cost as they grow.