Insurance choices should reflect the specific risks that most threaten daily operations and long-term goals. For leaders with limited resources, a clear prioritization framework prevents spending on low-impact coverages while leaving critical exposure unprotected. This article outlines a practical approach to align coverage decisions with business activities, cash flow and growth plans. Use these steps to create a focused, adaptable insurance plan that supports resilience without unnecessary complexity.
Identify Core Operational Risks
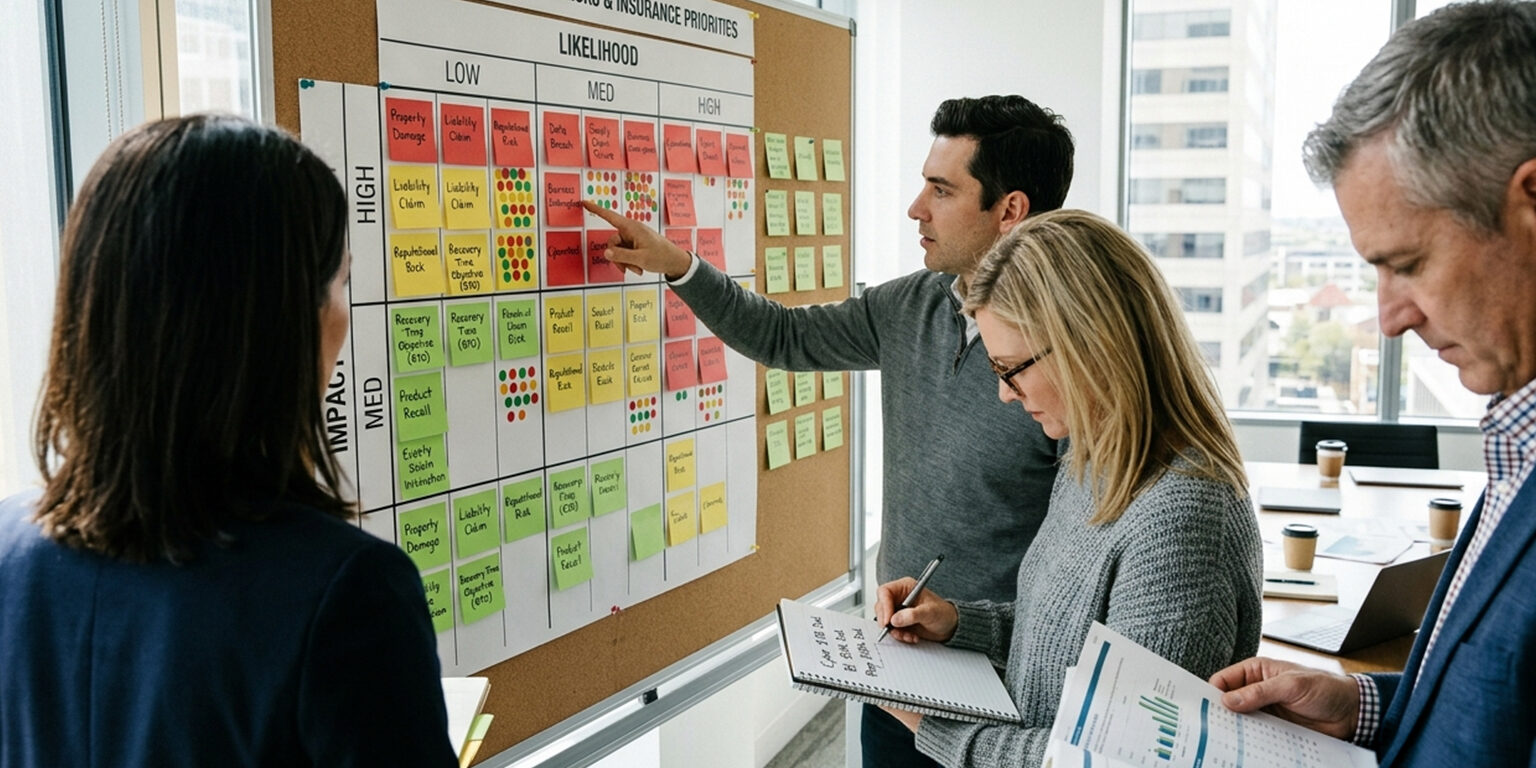
Start by listing activities that, if disrupted, would most harm revenue or reputation. Consider supply chain interruptions, key-person absence, property damage, and client liability as examples tied directly to your business model. Quantify potential loss ranges where possible to separate high-impact from low-impact risks. Prioritizing by likely financial and operational effect makes trade-offs clearer when budgets are constrained.
Documenting scenarios helps when discussing options with brokers and carriers. A concise risk register becomes a reference for future reviews and policy updates.
Match Coverage to Financial Capacity
Choose limits and deductibles that reflect both potential loss and your tolerance for short-term cash strain. Higher deductibles lower premiums but require reserves to cover self-insured losses; lower limits reduce premiums but may leave gaps. Balance premium savings against the probability and severity of losses to find sustainable cover. Regularly revisit this balance as revenue and margins change.
Build a contingency fund sized to your chosen deductible or common small losses. That fund reduces the pressure to file frequent claims and supports more affordable long-term pricing.
Prioritize Policies by Recovery Speed
Some coverages accelerate recovery more than others — for example, business interruption or cyber response policies can restore operations quickly after an incident. Identify which policies shorten downtime and protect customer relationships, and rank them higher. Coverages that only replace assets without addressing income loss may be secondary priorities for some businesses. Focus on protections that preserve cash flow and customer continuity.
When time-to-recovery is central to survival, investing in rapid-response coverage often yields better ROI than broader but slower protections.
Manage Carriers and Terms Intentionally
Beyond price, evaluate insurers on claims responsiveness, policy clarity, and available endorsements that match your needs. Policies with ambiguous language or frequent exclusions create uncertainty at claim time. Negotiate terms like sublimits, coinsurance, and business interruption triggers to avoid unpleasant surprises. A reliable carrier relationship simplifies renewals and adjustments as your business evolves.
Use renewal periods as checkpoints to update exposures and remove irrelevant coverages. Small, regular adjustments keep the program aligned with changing operations.
Conclusion
Prioritize insurance that reduces the biggest threats to cash flow and customer trust, not every conceivable risk. Match limits and deductibles to your financial capacity and favor coverages that speed recovery. Regularly review priorities to keep the program lean, relevant, and supportive of growth.