Insurance often feels like a list of policies rather than an integrated part of operations.
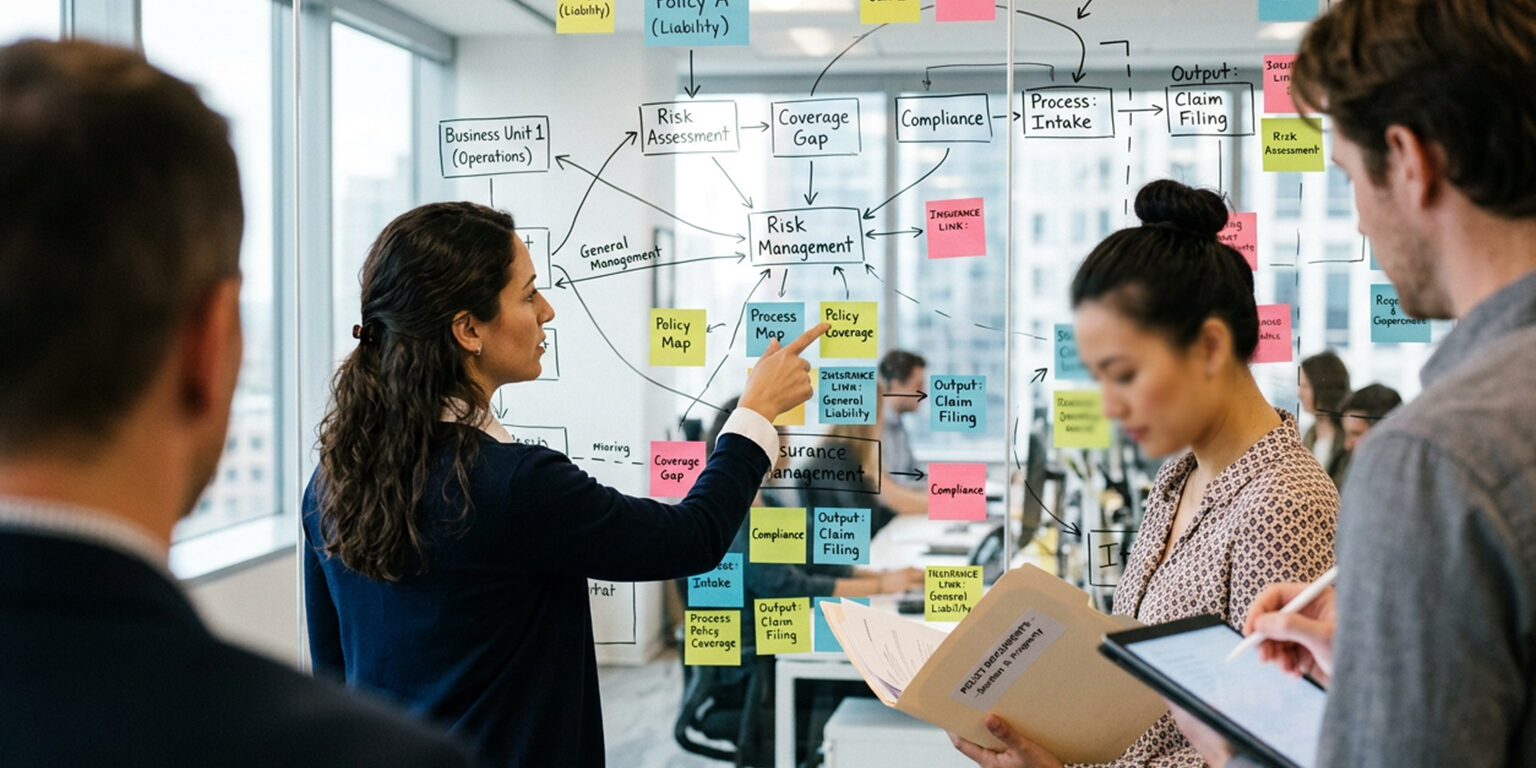
Mapping coverage decisions to business processes changes that perspective and makes protection actionable.
This approach clarifies which activities truly need transfer of risk, where retention is acceptable, and how controls reduce premiums.
It also creates a repeatable framework for future changes.
Process-driven risk mapping
Start by documenting core processes: sales, service delivery, supply chain, payroll, and IT. For each process identify exposures, likely loss scenarios, frequency and potential impact. Engage process owners to validate assumptions and surface controls already in place. Treat near-misses as signals for coverage needs as much as actual losses.
This map becomes the baseline for coverage decisions and helps avoid redundant policies. It also guides cost allocation by function.
Selecting coverage by criticality
Use the process map to rank exposures by criticality — what disrupts revenue, compliance, or reputation. Match coverages to the ranked list: primary policies should protect critical functions while secondary layers cover lower-impact risks. Consider self-insurance for routine, low-severity risks, and allocate budget to risks with systemic outcomes. Insurers often price coverage based on demonstrated controls, so tie mitigations to policy terms.
- General liability — service delivery and premises
- Professional liability — advice, contracts, and direct services
- Property and business interruption — locations and key suppliers
This targeted approach keeps premiums aligned with business priorities. It also simplifies renewal conversations with brokers.
Governance, review rhythm, and documentation
Establish a governance rhythm that reviews the process map and policies after key changes or on an annual schedule. Define roles for who updates process exposures, who approves coverage changes, and who manages claims. Maintain concise documentation linking each policy to the processes it protects and the rationale for limits or deductibles. This evidence helps underwriters and improves negotiating leverage.
A clear review cadence prevents coverage gaps during growth or change. It also turns insurance from a compliance task into a strategic asset.
Tracking metrics and claims trends
Track a small set of metrics tied to processes: frequency of incidents, time to recover, claim amounts, and control failure rates. Use these KPIs to tell a clear story to underwriters and to prioritize investments in controls. Regularly review claim trends to spot patterns that insurance should or should not cover. Integrate these metrics into financial forecasts so premiums and retained losses are visible to leaders.
Data gives bargaining power when negotiating terms or pricing. It also makes the coverage roadmap defensible and measurable.
Conclusion
Structuring insurance decisions around business processes makes coverage purposeful.
It improves budgeting, strengthens controls, and focuses protection where it matters most.
Start small, document decisions, and iterate as the business evolves.