Insurance can feel like a spreadsheet of worst-case scenarios, but sensible choices start with what actually keeps your doors open. Focusing coverage where a loss would interrupt revenue or destroy key assets narrows options and preserves budget. This piece looks at practical ways to rank policies by operational importance and cash-flow impact. The goal is a resilient, affordable mix rather than every policy under the sun.
Pinpoint What Keeps You Open
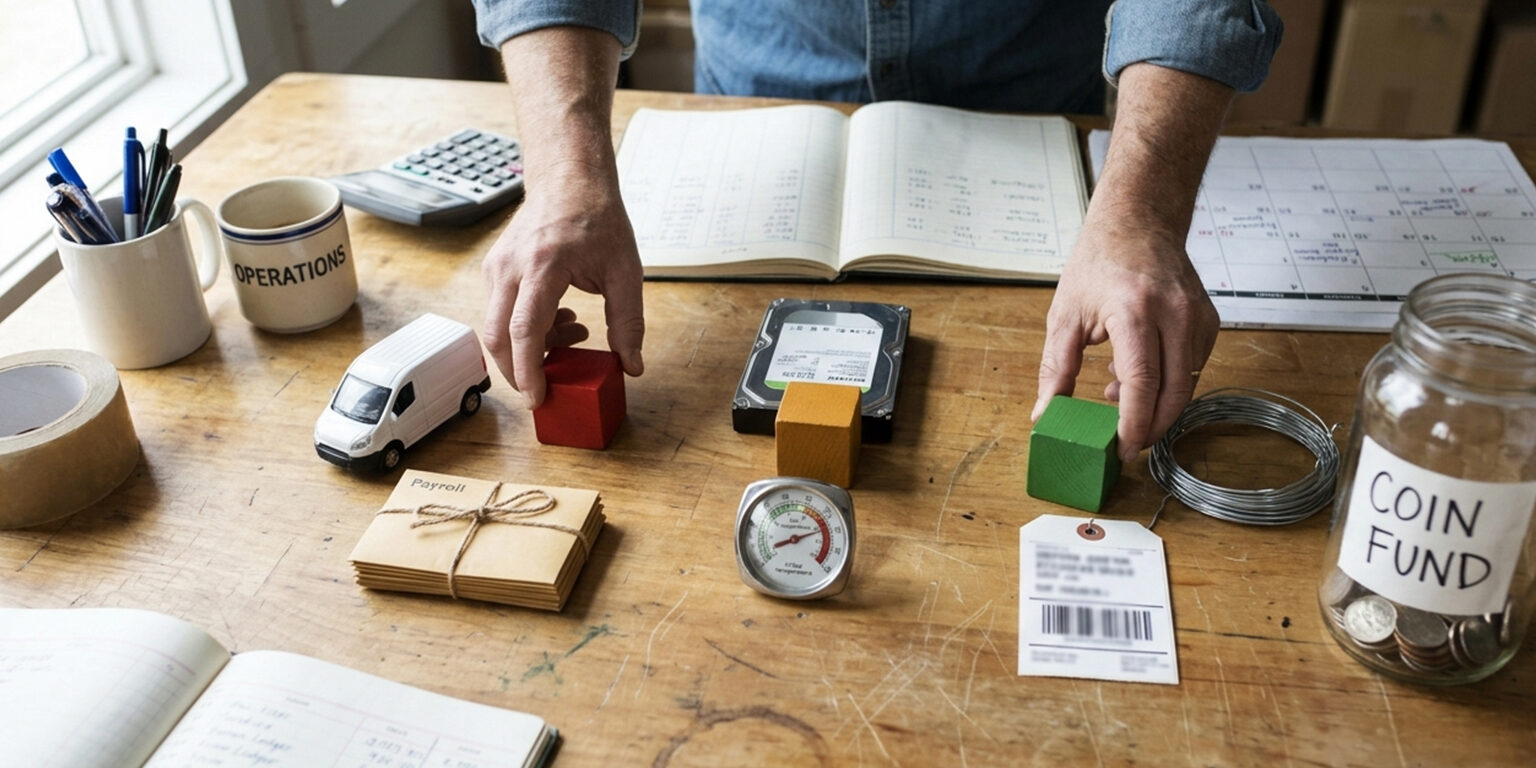
Begin by listing the people, equipment, and locations that would shut you down if damaged or lost. Think beyond replacement cost: consider lead times for repairs, dependency on a single supplier, and customer contracts that require continuity. A small restaurant, for example, may prioritize equipment breakdown and spoilage over a separate cyber policy at first. Use these priorities to designate which risks need immediate transfer to an insurer and which can be managed internally for now.
Quantify likely business interruption costs where possible, even if estimates are rough. Those figures help justify coverage levels and determine acceptable deductibles. Prioritizing this way keeps limited premium dollars focused on the exposures that threaten survival.
Match Policy Structure to Cash Flow
Policy details matter: limits, deductibles, waiting periods, and sub-limits shape how claims affect cash flow after a loss. A lower premium with a long waiting period can be painful if payroll and rent need to be covered immediately. Conversely, a higher deductible can free up monthly cash if you have a reserve to handle smaller losses. Look for features that pay quickly — agreed-value endorsements, expedited claim options, or advance payments for urgent expenses.
Review renewal terms well before expiration so adjustments are timed with budgets, not emergencies. Align policy changes with seasonal cash cycles and expected revenue bumps or dips. That reduces the chance of taking on unaffordable coverage or unexpected out-of-pocket costs when trouble hits.
Trim Premiums Without Leaving Gaps
There are practical ways to reduce cost without gutting protection: bundle coverages, increase deductibles selectively, and shop carriers every few years. Use risk control measures — improved security, documented maintenance, contract clauses — to lower loss frequency and qualify for discounts. Consider captive-friendly tactics like stop-loss layers if your loss profile and scale support them.
- Bundle business property and liability to earn multi-policy discounts.
- Raise deductibles on coverages that respond to frequent, small claims.
- Document controls to support negotiations and lower rates.
These moves should follow your priority list so savings don’t expose critical risks. Regular reviews keep the balance aligned with where your business actually needs protection.
Conclusion
Design insurance around the operations that would stop you from trading, not around abstract worst cases. Use measured trade-offs — deductibles, waiting periods, and endorsements — to protect cash flow while controlling premiums. Reassess priorities after any change so coverage stays practical and effective.