Improving a credit score rarely happens with a single dramatic move. Small, consistent adjustments to how you use credit and manage payments are the changes that add up. Over time they reduce the signals lenders watch and can lead to lower rates or better approval chances. You don’t need to overhaul your finances overnight to start seeing measurable progress.
Prioritize Payment Timing
Payment history and reported balances are two of the biggest drivers of score movement. Paying before your statement closing date — not just the due date — keeps the balance that gets reported to bureaus lower, which can immediately improve utilization-based scoring. Making two smaller payments each month instead of one large one also keeps reported balances down and reduces the risk of accidental late payment. Set autopay for at least the minimum and calendar a separate payment for the statement balance when possible.
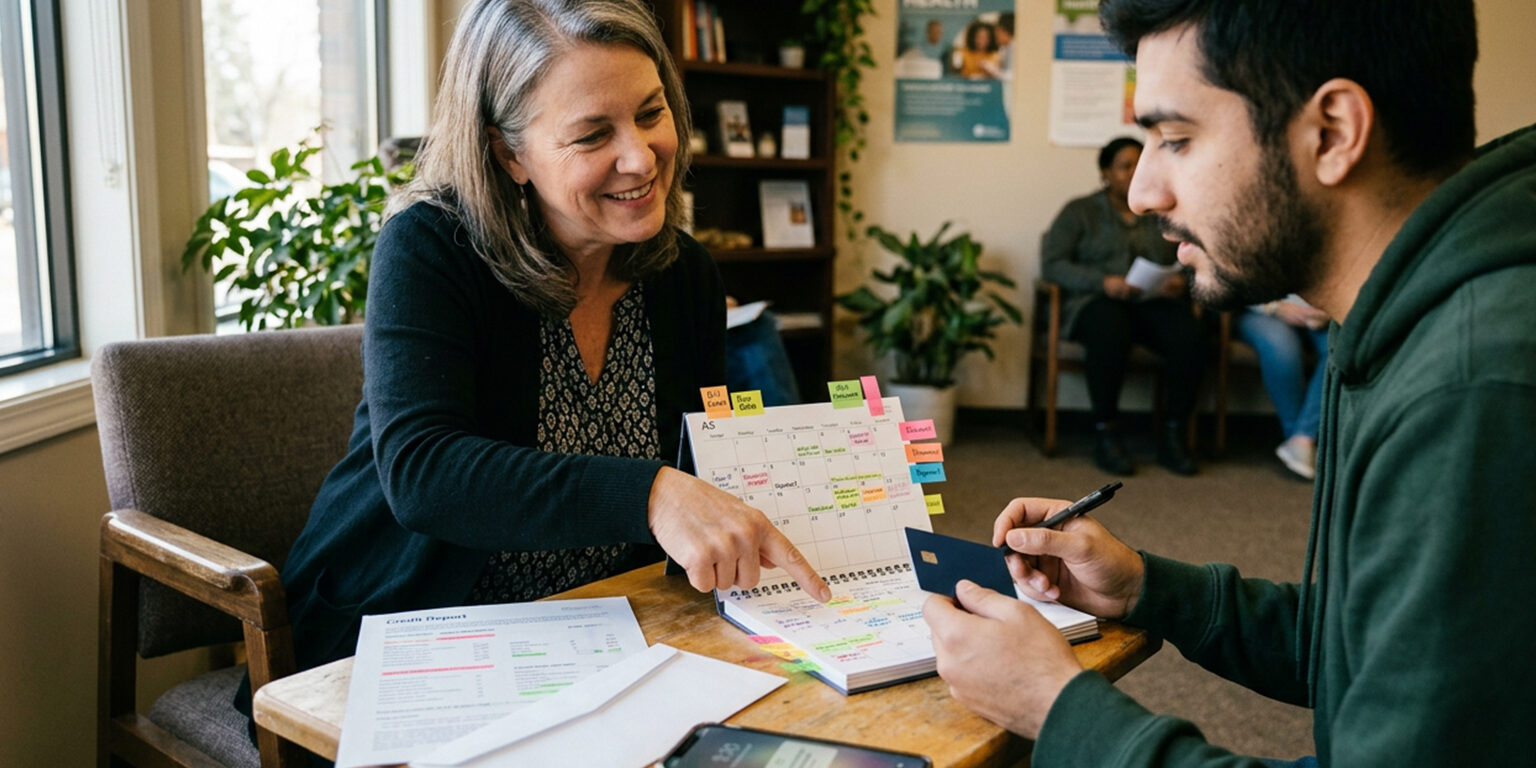
Practical steps include noting each card’s statement close and scheduling a payment a day earlier. Small calendar nudges remove forgetfulness and preserve on-time marks.
Trim and Balance Your Credit Use
Credit utilization is simple in concept but powerful in impact: lower balances relative to limits look better to scoring models. Aim to keep utilization below 30%, and try for under 10–20% when you want a noticeable lift. Avoid closing older accounts out of habit, because length of credit history and available limit both help your standing. If you need room for a big purchase, asking for a modest credit limit increase can help — only if you won’t treat it as extra spending power.
Use small recurring charges on seldom-used cards and pay them off to keep accounts active without carrying balances. That preserves limits and supports a healthier utilization ratio.
Repair and Monitor With Purpose
Errors on credit reports are common enough that periodic checks are worthwhile; disputing factual mistakes can remove incorrect negative entries. When dealing with collections, negotiate clearly and get agreements in writing before paying; ask for removal if a settlement is reached. Limit hard inquiries by spacing applications for new credit, since multiple inquiries can shave points in the short term. For rebuilding, consider a secured card or a credit-builder loan that reports reliably to the bureaus.
Set up free alerts or a monitoring tool to catch surprises early, and act fast when you see inaccuracies or unexpected drops. Quick, focused repairs often restore points faster than waiting for negatives to age off alone.
Conclusion
Small, targeted habits—timing payments, managing utilization, and monitoring reports—are the most dependable path to better scores. Pick two changes you can sustain this month and measure the difference on your next statement. Consistency matters more than perfection when you’re building credit momentum.