Organizing credit cards by defined roles reduces decision friction and helps you capture more value from everyday spending. A segmentation approach assigns specific responsibilities to each card so rewards, fees, and utilization work together instead of against you. It also makes routine reviews simpler and highlights opportunities to consolidate or cancel accounts. This piece outlines a practical way to segment cards, match them to behavior, and maintain healthy credit metrics over time.
Define Your Segments
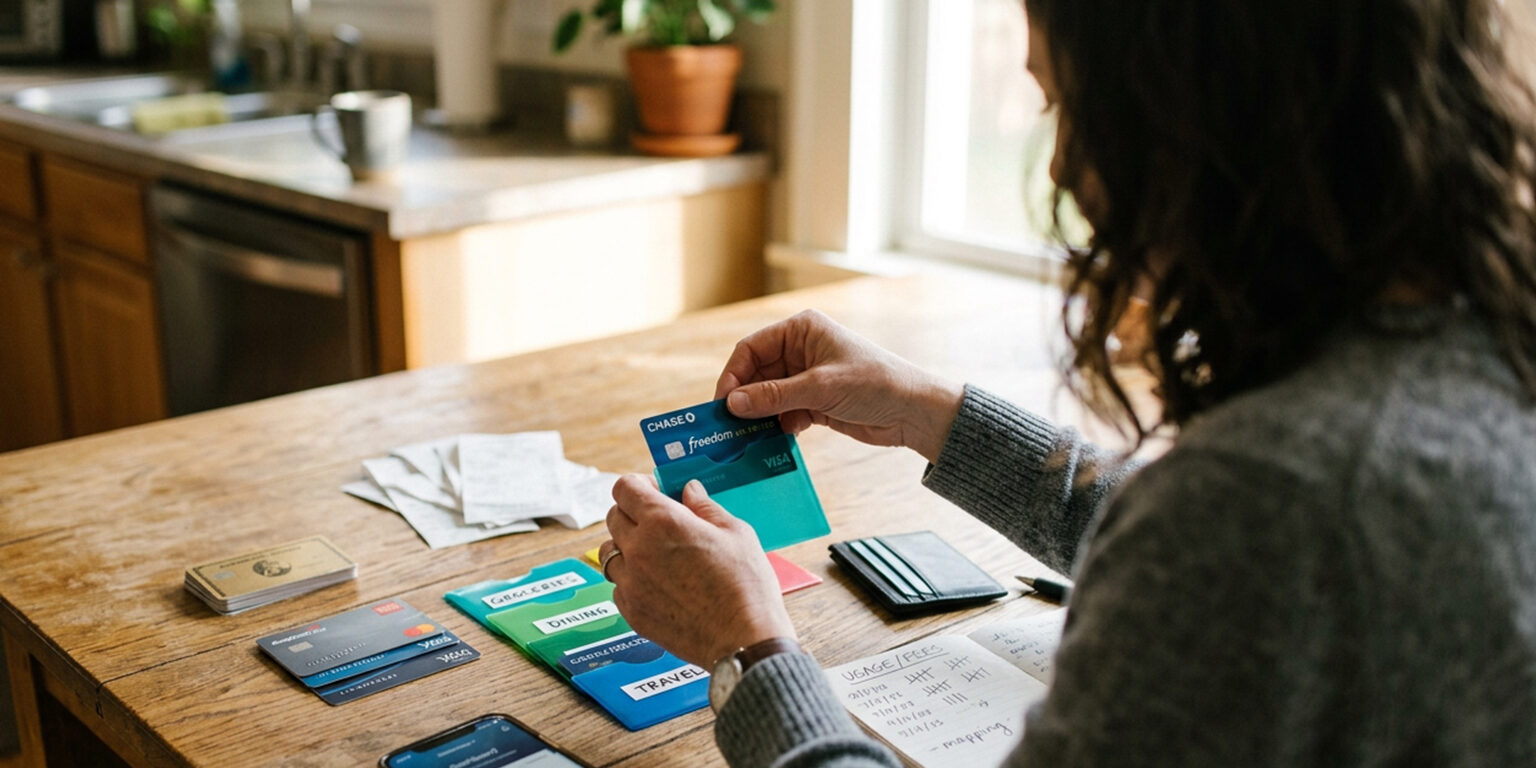
Start by identifying a small set of functional segments that match your life and spending patterns. Common segments include daily essentials, travel and dining, recurring bills, and backup or balance-transfer cards; choose only the ones that matter to you. Limit the total number to keep the system manageable and avoid swapping cards for every purchase. Clear roles prevent reward dilution and help preserve credit history across accounts for score stability. Naming segments explicitly makes it easy to communicate a household card policy or to follow rules while shopping.
After choosing segments, map each card to a single primary role and, occasionally, a secondary role. This reduces overlap and simplifies tracking without forcing you to carry every card all the time.
Match Cards to Spending Habits
Once segments exist, align each card’s rewards, categories, and benefits with the spending that happens most often in that segment. For example, a card with high grocery returns should be your daily essentials card, while a travel card that covers baggage or lounge access fits the travel segment. Consider annual fees against expected value: a card with a fee can be appropriate if its benefits and expected returns exceed that cost for the assigned role. Periodically review statements to confirm the match and adjust if your spending shifts.
- Daily essentials: groceries, gas, pharmacy.
- Recurring bills: utilities, subscriptions, streaming.
- Specialty: travel, dining, or seasonal spending.
Use simple tracking rules to keep assignments consistent and avoid chasing temporary rotating categories unless the gain is meaningful.
Monitor Costs and Credit Health
Segmentation is not just about rewards; it’s also about managing fees, interest risk, and utilization. Keep utilization low across the overall credit line, not just per card, to protect scores and borrowing flexibility. Close costly or unused accounts carefully to avoid unexpected impacts on average account age and utilization. Automate recurring payments on the cards assigned to bills to avoid missed payments and late fees that negate reward value. Regularly assess whether a card still earns its place in your segmented wallet and be willing to replace it if better options arise.
Combine periodic reviews with a simple spreadsheet or app to monitor effective returns, fees, and utilization. This keeps the system practical and scalable as your needs change.
Conclusion
Segmenting cards by role simplifies decisions and increases realized value from rewards. It protects credit health by focusing usage and preventing unnecessary churn. With clear rules and periodic reviews, a role-based wallet becomes both efficient and resilient.