Many people collect credit cards without aligning them to when money arrives and where it is spent. Organizing cards around predictable income and expense rhythms reduces fees and increases value. This approach focuses on timing — where you put spending and when you pay it — to improve rewards and cash management. It makes credit easier to manage across pay periods and seasonal changes. It works for single individuals and households alike.
Map Your Cash Flow Patterns
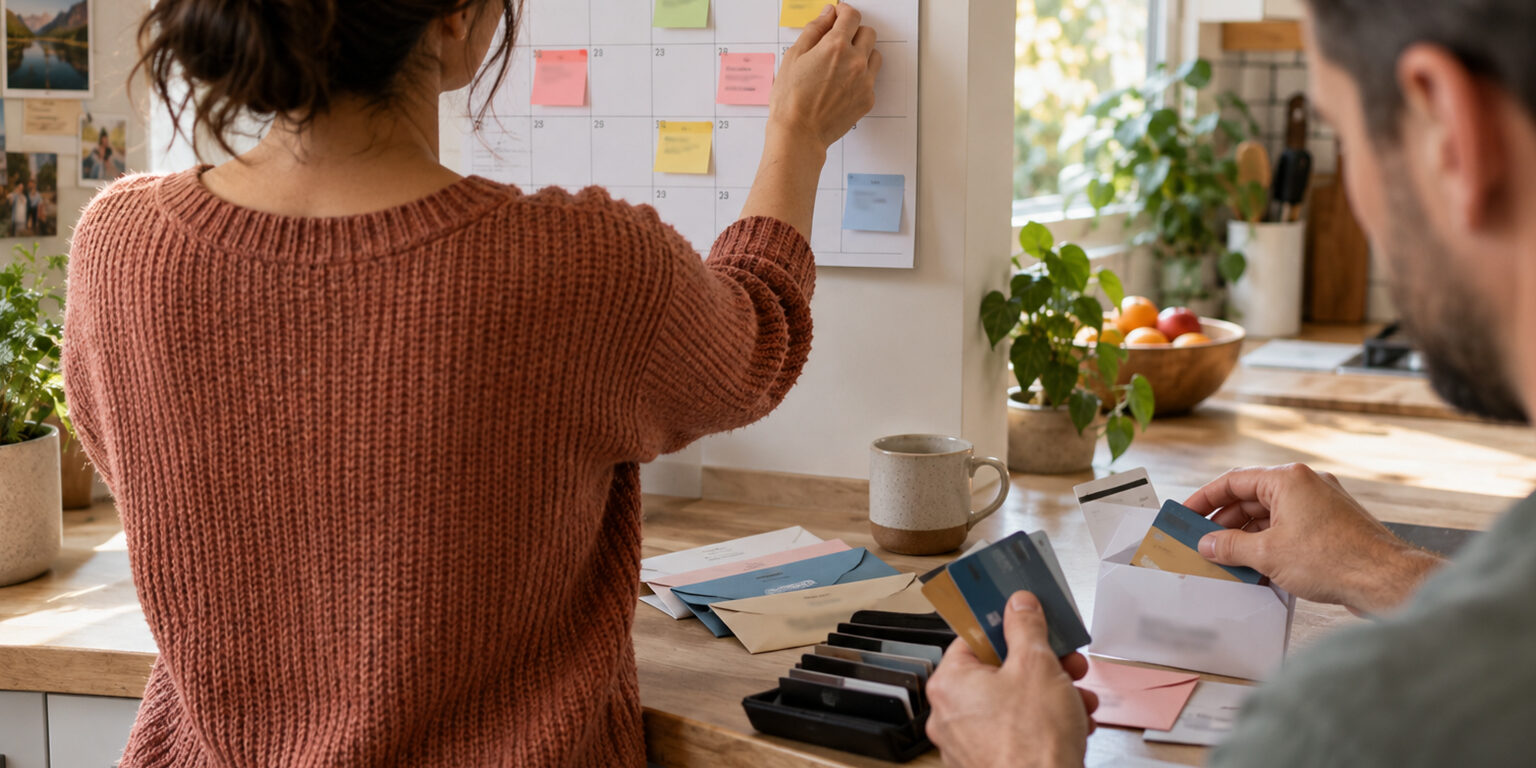
Start by tracking deposit dates, bill due dates, and major recurring expenses across a typical month or quarter. Note seasonal shifts such as higher utilities or quarterly tax payments, and identify weeks with tighter liquidity. Understanding these patterns helps you choose cards that maximize interest-free float and match billing cycles to paydays. Record the statement close date for each card so you know when balances are reported.
With a clear calendar, you can prioritize cards that offer grace-period advantages for large outflows. That reduces the need to carry balances or pay unnecessary interest.
Assign Specific Roles to Cards
Give each card a single, deliberate role: everyday rewards, bills and subscriptions, big purchases, or emergency backup. Assigning roles prevents overlap and lets you concentrate spending to reach bonus categories quickly. Choose a billing cycle that ensures large charges post after a paycheck and before the due date to maximize float. If you use multiple cards for rewards, rotate them predictably so reconciliation and payments stay simple. Confirm each card’s bonus categories align with where you already spend to avoid chasing marginal value.
- Everyday card for groceries and recurring places.
- Bills and subscriptions on a low-fee statement cycle.
- One backup card for large purchases and emergencies.
Clear roles also make it easier to spot fraud and reconcile monthly statements. Keep one low-cost card for low-usage accounts to preserve credit history without fees.
Control Costs and Monitor Health
Regularly review annual fees, interest rates, and reward redemption rates against actual benefit. Some cards are worth a fee only when you use their specific benefits within your cash flow pattern. Watch utilization across cards and avoid transfers that spike reported balances near statement dates. Use alerts and simple spreadsheets to spot unexpected fee changes or category shifts.
Schedule a quarterly review to cancel or replace underperforming cards and to adjust roles as income shifts. Small maintenance prevents fee creep and preserves credit score resilience.
Conclusion
Matching cards to cash flow cycles makes rewards easier to capture. It also reduces carrying costs and simplifies monthly management. Start with a calendar, assign roles, and review quarterly.