Good credit is built by consistent, small decisions rather than dramatic moves. This article outlines practical daily and weekly rhythms you can adopt to steady your score and strengthen borrowing options. The focus is on manageable habits: payment timing, utilization awareness, and regular monitoring. Follow these steps to create momentum without overcomplicating your finances.
Set a Weekly Payment Rhythm
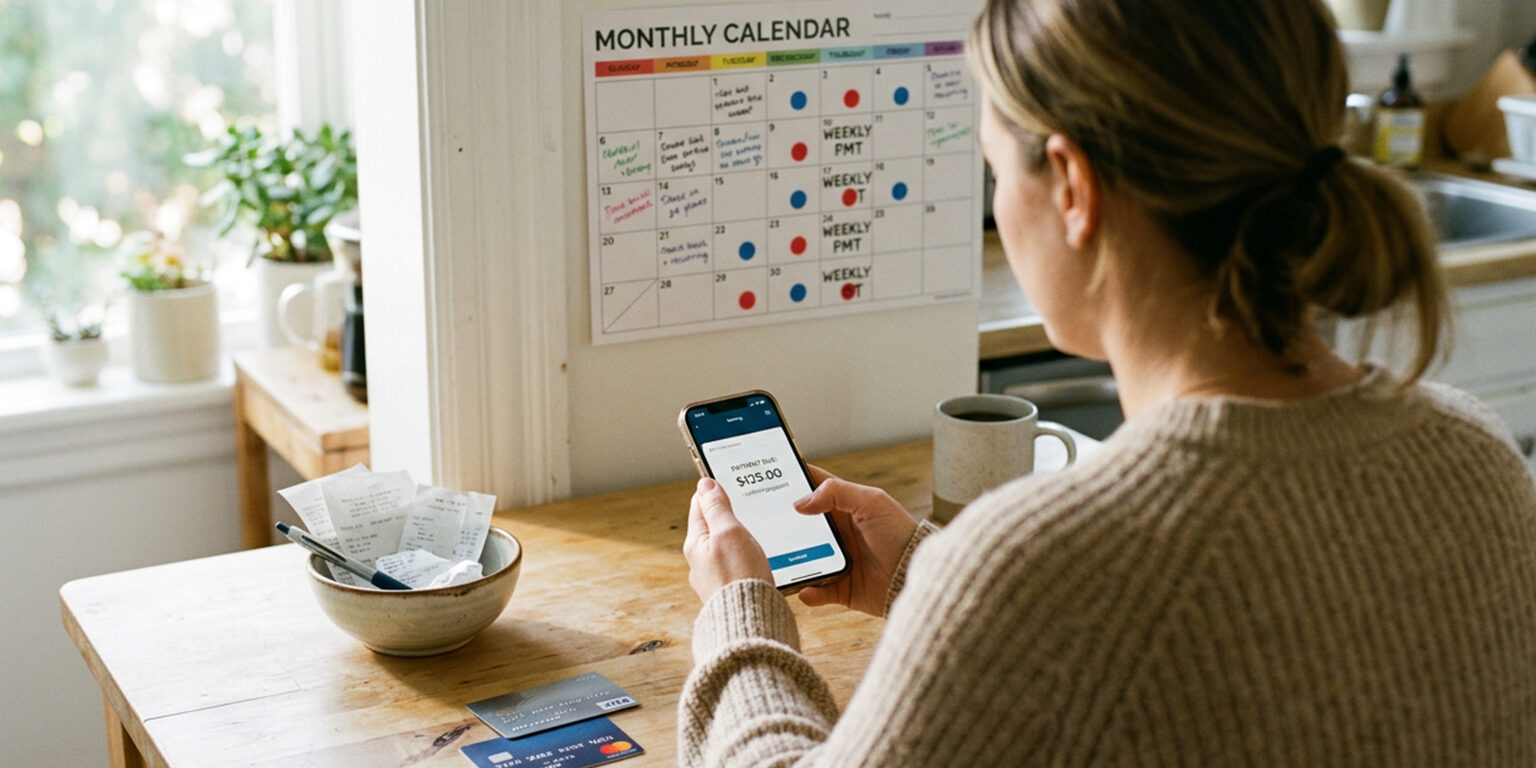
Paying on time remains the single most powerful influence on your credit profile. Schedule a consistent weekly check to clear upcoming bills, set autopay for essentials, and make partial payments when balances are high. Breaking monthly obligations into smaller weekly transfers reduces the chance of a late payment and helps keep card balances lower through the month. Review your upcoming statement a few days in advance to catch surprises. This routine also makes cash flow predictable and reduces stress.
Start with one recurring day and refine it to match your pay schedule. Small, repeatable actions compound over months. Consistency matters more than perfect timing.
Optimize Credit Utilization
Credit utilization — the percent of available credit you use — is a key component of scoring models. Aim to keep balances low relative to limits by spreading purchases across cards or making an interim payment before the statement posts. When you use cards strategically, prioritize leaving enough unused credit to absorb unexpected costs. If a high balance is unavoidable, consider increasing your available credit only after confirming you will maintain discipline. Regular, modest payments can keep reported utilization within healthier ranges.
- Track statement dates to time payments
- Request modest credit line increases cautiously
- Use alerts to monitor balance thresholds
These practices keep utilization visible and under control. They also signal reliable behavior to issuers. Over months this behavior lowers risk and improves score stability.
Monitor Reports and Dispute Errors
Regularly reviewing your credit reports helps catch mistakes and fraud before they damage your score. Check reports at least monthly using free tools and review for unfamiliar accounts, incorrect balances, or duplicate listings. Also check for identity flags such as unfamiliar contact details or hard inquiries you did not authorize. Document any discrepancies and follow each bureau’s dispute process promptly to remove inaccuracies. Timely disputes and confirmations of corrections will gradually improve the accuracy of your profile.
Monitoring also gives you a clearer sense of long-term trends so you can adjust behavior. Combine report checks with periodic reviews of your budget and goals. If you find fraud, notify your issuers immediately to limit damage.
Conclusion
Improving credit is a marathon of consistent, manageable choices. Implement a weekly payment habit, mind utilization, and review reports regularly to build momentum. Over time those small rhythms produce measurable gains.